The construction materials market in Ukraine is set by what is funded and actually built, and in 2025 that came to UAH 258.2bn of construction work, roughly USD 6bn at that year's exchange rates. Assessed recovery and reconstruction needs for the ten years to 2035 stand at USD 587.7bn in the fifth Rapid Damage and Needs Assessment, published in February 2026 by the Government of Ukraine, the World Bank Group, the European Commission and the UN. Spread evenly, that requirement would be almost ten times the value of everything Ukrainian contractors performed last year, which is why a share of the headline figure is not a usable estimate of demand for any building material.
Four quantities sit between the damage and a purchase order, and each is narrower than the one before it. Assessed need is a cost of restoration that includes social payments, demining and equipment. Funded demand is the part that has money behind it, and for 2026 the government reported USD 5.8bn available against priorities of USD 15.25bn. Executed construction is what contractors actually build, and it fell in volume through the first seven months of 2026. Demand for a particular material is narrower again, because it depends on who specifies and buys within each pool of work.
Ukrainian statistics have excluded occupied territories and areas of active hostilities since 2022, so comparisons with 2021 also reflect a change in coverage.
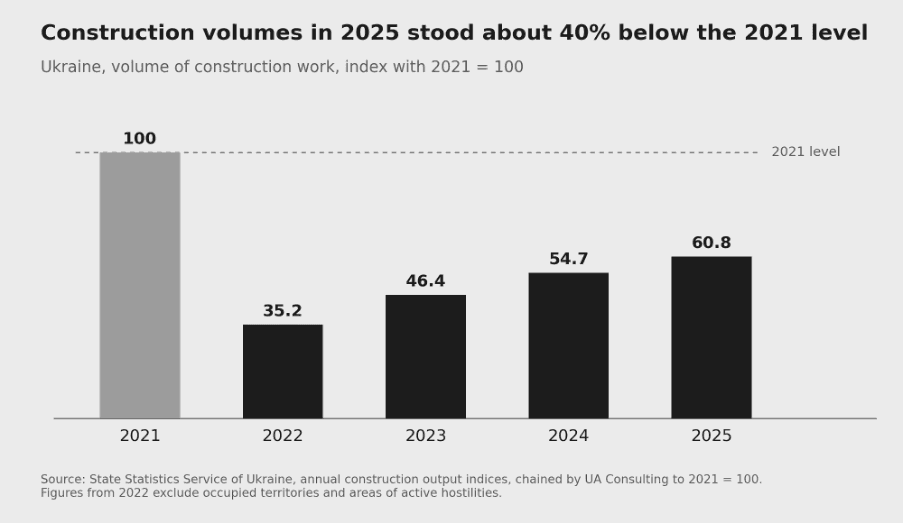
Chained from the annual construction output indices of the State Statistics Service of Ukraine, as reported for 2022 and, after revision, for 2023 to 2025. In January to July 2026 the volume of construction work was 11.2% lower than a year earlier.
Reconstruction needs, funding and executed work
The RDNA5 main report defines needs as the cost of repair, restoration and reconstruction at market prices at the end of 2025, including a premium for rebuilding to improved standards and allowances for inflation, surge pricing and higher insurance. The estimate has risen with each edition of the assessment from USD 349bn in 2022, and the report attributes the latest increase to continued damage, improved data, methodological refinements, inflation and exchange-rate movements. Transport accounts for the largest share at USD 96.3bn, ahead of energy at USD 90.6bn and housing at USD 89.8bn.
A substantial share of the assessed reconstruction need does not translate into demand for construction work or building materials. Social protection needs of USD 42.7bn consist mainly of benefit payments and employment measures, explosive hazard management accounts for USD 27.6bn, and of the USD 63.3bn assessed for commerce and industry, USD 37.4bn concerns the restoration of services rather than the rebuilding of premises. In energy, USD 70.8bn relates to the power system, where generation assets account for most of the recorded damage. Geography narrows the addressable part further, since Donetsk, Luhansk, Zaporizhzhia and Kherson oblasts, large parts of which are occupied or close to the front line, account for just over 40% of assessed needs.
Very little of the assessed need has become completed work. RDNA5 records at least USD 20.3bn of needs met between February 2022 and December 2025, equivalent to 3.5% of the ten-year total, and notes that data on needs met are incomplete in several sectors. For 2026 the government selected priority investment projects and programmes worth USD 15.25bn. At the presentation of the assessment the responsible ministry reported USD 5.8bn of available funding against a gap of USD 9.5bn, with the largest shortfalls in energy, housing, transport, and water supply and sanitation. Heat supply alone required USD 1.6bn in 2026, of which less than 1% had been secured, and the priority list also contains programmes outside construction such as demining and economic support.
External finance has grown, although much of it supports the state budget, energy imports or bank lending rather than building work. The EU's Ukraine Facility releases funds against reform commitments under the Ukraine Plan and had disbursed more than EUR 29.5bn by mid-2026, mostly as budget support. At the Ukraine Recovery Conference in June 2026 the European Commission announced the first disbursement of EUR 3.2bn in budget support under the separate EUR 90bn Ukraine Support Loan, alongside the first instalment of a EUR 6bn defence package. The same announcement put commitments under the Ukraine Investment Framework at EUR 8.5bn, which the Commission expects to mobilise nearly EUR 26bn in public and private investment. The EBRD deployed a record EUR 2.9bn in Ukraine in 2025, of which more than EUR 1.2bn went to energy security, and its energy financing that year helped procure 2.3bn cubic metres of gas. The bank has separately supported the grid operator Ukrenergo in buying 43 autotransformers and building 36 associated protective structures.
The availability of public funding remains constrained by Ukraine’s broader fiscal position. In mid-September 2026 the prime minister described the state of public finances as close to critical and warned that Ukraine could lose a significant part of USD 29.5bn in planned international financing if parliament did not pass the required legislation on schedule. These figures also belong to different stages and cannot be added or set against each other, since a ten-year requirement, a single year of priority programmes, a multi-year investment commitment and one year of executed construction each measure something different.
Construction output, prices and capacity constraints
Ukrstat's construction output index measures changes in the physical volume of work, and it rose by 6.8% in 2021 before falling to 35.2% of the 2021 level in 2022. After revisions, Ukrstat reports volume growth of 31.8% in 2023, 17.8% in 2024 and 11.3% in 2025, so each year of the recovery added less than the one before it.
In current prices, output in 2025 was broadly equal to the UAH 258bn recorded in 2021, and a ministry analysis of the sector concluded that construction had exceeded its pre-war level on several indicators. Prices account for most of that apparent recovery. Construction and installation prices had already risen by 17.5% in 2021 and then rose by 27.4% in 2022, 15.8% in 2023, 7.9% in 2024 and 5.8% in 2025, a cumulative increase of about 68% after 2021. Deflating nominal output by those published indices puts the physical volume of work in 2025 roughly 40% below the 2021 level, and chaining the annual volume indices gives a similar answer of about three fifths of 2021. Both are calculations from published series rather than official statistics, and part of the difference reflects the narrower territorial coverage of the data since 2022.
Engineering structures such as roads, bridges and utility networks accounted for about 53% of output in 2025, against about a third for non-residential buildings and 13% for housing. Repair, reconstruction and technical re-equipment together made up 60% of all work carried out.
The recovery then reversed, with the volume index 3.3% higher year on year in January before cumulative output ran 1.8% lower in January and February, 6.5% lower in January to May and 11.2% lower in January to July. July output was 25.9% below July 2025, with engineering structures down by 36% and non-residential buildings by 15.9%, while residential construction rose by 0.5%.
Prices moved the other way, with construction and installation work 23.1% more expensive in June 2026 than a year earlier against an increase of 5.8% for 2025 as a whole. Industrial producer prices covering manufacturing and energy supply were 45.2% higher in May than a year before, so hryvnia turnover overstates physical activity in 2026 by a wider margin than in earlier years.
Builders themselves report supply-side constraints far more often than weak demand. In Ukrstat's business survey for the third quarter of 2026, 53.6% of construction companies expected labour shortages to restrict activity and 47.9% cited financial constraints, against 20.7% citing insufficient demand. Order books covered six months of work on average, and about a quarter of respondents expected to reduce staff. RDNA5 finds the same pattern across the economy, where firms name skilled labour shortages as their principal production constraint. Falling volumes alongside rising prices are consistent with those constraints, although the published data do not separate them from higher energy, materials and logistics costs. The wider economy grew by 0.4% year on year in the second quarter of 2026.
Housing completions and new residential permits
Completions and new permits have moved in opposite directions since 2021. Completed residential floor area fell from 11.4m m² in 2021 to 7.1m m² in 2022, then rose by 21.1% in 2024 to 9.76m m² before easing by 2.1% to 9.55m m² in 2025. The floor area covered by new residential construction permits fell further and stayed low for longer, from 12.7m m² in 2021 to 3.9m m² in 2024, before rising by 49.4% to 5.8m m² in 2025.
In every year since 2022 completed floor area has exceeded newly permitted floor area, which market commentaryattributes to developers finishing projects started before the full-scale invasion while postponing new launches. Even after the 2025 increase, permitted area remained below half of its 2021 level. Permitted floor area in the second quarter of 2026 was 6.1% higher than a year earlier, while permits for multi-apartment buildings across the first half of the year were 2.3% lower. Materials demand from housing over the next few years depends on how many approved projects actually start.
Funded demand in 2026 and how it is purchased
Demand for building materials in Ukraine can be traced to several funding pools that differ in who pays and in who decides what is bought.
Demand pool | Who pays | Who decides what is bought |
Repair of damaged homes | Households, using eRecovery compensation | The household, at stores and contractors registered in the programme |
Replacement and new housing | Certificate holders and private buyers | Developers and their contractors, before the home is sold |
Protective works at energy sites | State budget reserve fund, state companies, IFI loans | Regional administrations and state companies, through general contractors |
Transport, energy and municipal projects | State and local budgets, IFI loans, EU guarantees | Asset owners and their designers, then contractors |
Logistics and industrial buildings | Private developers, occupiers and lenders | Developers and their design-build contractors |
Household repair and housing compensation
The state eRecovery programme channels public compensation to households, and by 10 July 2026 it had paid UAH 119.1bn to 231,681 families. Compensation for damaged homes, implemented within the World Bank's HOPE project, accounted for UAH 14.8bn across more than 153,000 families, up from UAH 11.8bn and about 121,400 families in December 2025. Average payments ran at UAH 69,900 for minor repairs and UAH 340,900 for major ones. The money reaches materials suppliers through a dedicated card that can be spent on building materials or contractor work, and only stores and contractors registered in the programme can accept it.
Housing certificates for destroyed homes are a larger strand at UAH 96.9bn across more than 74,000 families, of whom more than 33,000 had bought a home by July. Since December 2025 the programme has also issued vouchers of UAH 2m to displaced people from occupied territories who are combat veterans or have war-related disabilities, with 3,296 applications worth UAH 6.59bn approved in the first funding round. More than four fifths of everything paid under the programme has financed the purchase of housing rather than repair materials, which places that money with developers and sellers rather than at the builders' merchant.
Protective works at energy sites
Physical protection of energy facilities became one of the larger identifiable construction programmes of 2026 after attacks in the autumn and winter of 2025 left much of the country without power and heating. Since March, public bodies have tendered protection for nearly 250 substations, transformers and cogeneration units worth UAH 24.3bn, close to a tenth of all construction work performed in 2025. Most of it is financed from a UAH 22.06bn allocation out of the state budget reserve fund approved by the Cabinet of Ministers on 20 March 2026 and procured through regional state administrations. Room for further allocations of that kind is limited, because the reserve fund had already released UAH 47.5bn by the end of March, close to its legal ceiling of 1% of general-fund expenditure.
The state Restoration Agency is building engineering protection at more than 100 critical-infrastructure sites and publishes data on the construction materials bought for that work. The materials involved are concrete and reinforcing steel in volume, and GMK Center, citing the steel trader Metinvest-SMC, reports that rebar consumption rose by 26% to 447,000 tonnes in the first half of 2026, mainly because of infrastructure projects and protective structures at energy facilities.
Internationally financed projects
Internationally financed projects reach the construction market through the organisations that own the assets. EBRD financing in 2025 went to state companies including Naftogaz and the state railway operator, to urban transport, wastewater and district heating projects in five regional cities, and to private companies. Part of the support under the Ukraine Investment Framework reaches borrowers as bank lending to small and medium-sized enterprises. Demand for materials arises only once an asset owner commissions works and its contractors buy the inputs, and the conditions for taking part are set by each programme, a subject covered in our analysis of how companies take part in Ukraine's reconstruction projects.
Private logistics and industrial construction
Private logistics construction has continued through repeated destruction. Developers delivered about 216,000 m² of new warehouse space in 2025, the highest annual volume since 2008 according to market data, and attacks then destroyed around 300,000 m² in the first half of 2026. Developers and their contractors choose the building systems for these projects themselves, which makes them the most direct commercial counterparty available to a supplier of envelope and structural products. RDNA5 estimates that private capital could finance up to 40% of recovery needs over the decade, conditional on reforms to the business environment, access to finance and labour supply.
Domestic supply and imports by material category
National and sector data give no support to a general shortage of building materials, and the supply position differs by product.
Material | Domestic supply position | Role of imports |
Cement | Output about 8m tonnes against domestic use of about 6.3m tonnes | About 40,000 tonnes in 2024, with 23% of output exported |
Rebar and other long steel | Mills at about 55% utilisation in 2025, both main plants stopped by strikes in August and September 2026 | 46.1% of all steel consumed in January to July 2026, mostly flat products |
Float glass | No operating float line, three projects targeted at 2028 to 2030 | Effectively the whole market, about 11.2m m² in 2023 |
Plasterboard and dry mixes | Kyiv plant operating, Borshchiv dry-mix line producing since August 2025 | Not quantified in published statistics |
Insulation and envelope systems | Kingspan campus near Lviv under construction since April 2025 | Not quantified in published statistics |
The sources behind these rows differ, running from producers' associations and steel-market analysts to an investment guide presented at an international conference, so the categories are not strictly comparable with one another.
Cement
Cement production fell from 11m tonnes in 2021 to 5.4m tonnes in 2022 and recovered to 7.93m tonnes in 2024, with producers treating about 8m tonnes a year as the practical ceiling under current risks and logistics according to an Experts Club analysis. Domestic consumption fell from about 10.6m tonnes in 2021 to around 6.3m tonnes in 2024, when imports came to only about 40,000 tonnes, while exports rose from about 56,000 tonnes in 2021 to 1.7m tonnes in 2024. A September 2026 industry report put exports at 23% of output, with Poland the main destination, so output currently exceeds domestic use and the balance leaves the country.
Further investment in cement capacity depends on the recovery of domestic consumption rather than on assessed reconstruction need. At a 2024 briefing by the producers' association Ukrcement, restoring the plants in Balakliia and Kramatorsk was named as one route to higher output. Two producers were also reported to be considering new clinker kilns with combined capacity of 2.4m tonnes, to be built once consumption reached about 10.5m tonnes. Foreign capital has entered the category by buying existing assets, and in 2024 the Irish building-materials group CRH completed the purchase of two Ukrainian cement plants from Buzzi for EUR 100m, a transaction whose conditional competition clearance Ukraine's Supreme Court upheld in September 2025.
Steel and reinforcing bar
Ukrainian steel output fell from 21.3m tonnes in 2021 to 6.26m tonnes in 2022 and stood at 7.41m tonnes in 2025. Imports took a growing share of domestic consumption over the same period, rising from 22.6% in 2021 to 37.6% in 2024and then to 40.1% in 2025 and 46.1% in January to July 2026. Flat products make up about two thirds of those imports and rails arrive from abroad, including under donor aid. In spring 2026 the OECD cut its estimate of Ukrainian steelmaking capacity from 38.7m tonnes to about 8m tonnes a year, close to actual output.
Long products used in construction show imports and unused domestic capacity side by side, since GMK Center reported the rebar and wire-rod mills of ArcelorMittal Kryvyi Rih and Kametstal running at about 55% of capacity in mid-2025 while competing with imports on price. That capacity then contracted sharply, as Zaporizhstal and Kametstal both stopped production after strikes in August and September 2026 and their owner Metinvest declared force majeure on some contracts without giving a restart date. National steel output fell to 277,000 tonnes in August, 57.3% below August 2025, and GMK Center expects a weaker September. Installed capacity says little about the steel a contractor can actually buy in the second half of 2026.
Float glass
Ukraine has no operating float glass line, its only sheet-glass plant in Lysychansk sits in occupied territory, and consumption of 11.2m m² in 2023 was met from abroad. The Ukraine Investment Guide 2026, presented at the Ukraine Recovery Conference in Gdańsk, expects reconstruction to lift demand to at least 27m m² a year. It lists three domestic float projects with combined planned capacity of 73.7m m², which under an optimistic scenario would start production between 2028 and 2030. Most of the money behind them has yet to be raised, with NovaSklo having invested USD 5.2m of a planned USD 306.5m before 2026 and Ukrglass USD 13.9m of USD 278.5m.
Import dependence of that kind establishes that foreign supply serves the market today. It says nothing about the margins a new supplier could earn, about access to the glass processors and window manufacturers who actually buy float glass, or about the position of a newcomer against exporters already serving those customers. Those questions are settled at product and company level.
Plasterboard and dry mixes
Published statistics do not give consistent national series for plasterboard consumption or imports, so the supply position rests on capacity data for the main producer. Knauf lost its Soledar plant, able to produce up to 60m m² of board a year, when the town was occupied in January 2023, while its Kyiv plant with capacity of about 25m m² stayed in operation. In January 2025 the company began building a EUR 150m facility in Borshchiv, where its main gypsum quarry is located, designed for 30m m² of board and 320,000 tonnes of dry mixes a year. According to the Ternopil regional administration, the first phase, a dry-mix plant, produced its first output in August 2025, with the plasterboard line planned as a second phase. The adequacy of domestic supply cannot be tested here the way it can for cement or steel.
Insulation and envelope systems
Insulation and envelope systems have the thinnest public evidence base of any category examined here. Developers warned in mid-2022 of a shortage of mineral wool after one of the largest plants, near Kharkiv, was destroyed, and no comparable national data on current production or imports have been published since. GMK Center notes that part of the galvanised and painted coil used in roofing and cladding is imported, although domestic output of painted coil has grown. Kingspan began construction of a EUR 280m campus near Lviv in April 2025 for insulation and related products, with most of the facility due for completion by 2030, which is capacity under construction rather than supply available to a customer now.
Logistics and product conformity
Import logistics
Sea import routes changed during 2026, when sustained attacks on ships and port infrastructure from July led most shipowners to suspend calls at the Greater Odesa ports and container lines including Maersk and CMA CGM rerouted Ukrainian cargo through Constanța. Shipping was still disrupted in September, when Russian strikes again targeted Odesa and the surrounding region, and cargo that used to pass through Odesa now moves through Romanian ports or by rail and road from the EU. Metinvest reported that bringing coal in by alternative routes raised its logistics costs by 50% to 60%.
Freight is a large share of the delivered price for bulk materials with a low value per tonne, while for engineered building systems higher transport costs mainly show up in inventory and working capital, which pushes a supplier towards holding stock inside the country.
Conformity requirements for construction products
Ukraine has been aligning its rules for construction products with EU law as part of its European integration commitments. A technical regulation adopted by the Cabinet of Ministers in 2006 governed these products until the Law on Providing Construction Products on the Market, adopted in 2020 to implement the approach of Regulation (EU) No 305/2011, entered into force on 1 January 2023. As a general rule the law requires a manufacturer to draw up a declaration of performance through the Unified State Electronic System in Construction and to apply the Ukrainian mark of conformity. Transitional provisions allowed the law and the earlier technical regulation to apply in parallel until 2025.
A wartime measure qualifies that position for goods arriving from the EU. Since March 2022 a Cabinet of Ministers resolution has allowed construction products imported from EU member states onto the Ukrainian market on the manufacturer's declaration of performance under Regulation (EU) No 305/2011, accompanied by a copy in Ukrainian. The measure runs until martial law ends and for 90 days afterwards. Because it was inserted into the earlier technical regulation, its application after the parallel period should be confirmed for each product, and goods outside its scope follow the national procedure.
Further alignment with the EU construction-products regime is planned but has not yet been completed. The EU is replacing Regulation (EU) No 305/2011 with Regulation (EU) 2024/3110, most of whose provisions have applied since January 2026 while parts of the older regime remain in force until 2040. In June 2026 the ministry presented a concept for transposing the new regulation that favours amending the existing law in stages, work tied to the internal market cluster of accession negotiations. Mutual recognition of conformity assessment would require an Agreement on Conformity Assessment and Acceptance of Industrial Products, which has not been concluded. Its first phase is expected to cover machinery, low-voltage and electromagnetic-compatibility products, described by the Government of Ukraine as a future agreement for those three sectors, none of which is construction products. Requirements for a specific product should be confirmed with qualified conformity-assessment or legal advisers.
Purchasing structure and routes to market
The purchasing structures above indicate which route to buyers fits which product, without settling the choice for any individual company. Where purchases are frequent, fragmented and dependent on local stock, as with materials bought with eRecovery funds at registered stores, a Ukrainian distributor or retail partner is the only practical way to be present at the point of decision. The value of that route rests on a partner's coverage, stockholding and sales capability, which can be established only partner by partner and is examined in our analysis of finding a distributor in Ukraine.
Where a small number of asset owners, developers or contractors account for most purchases and products are chosen at the design stage, access depends on engagement before works are tendered. The funding evidence for 2025 and 2026 identifies state energy and rail companies, municipal utilities and logistics developers as buyers of that type. Local production becomes relevant where volumes are predictable, freight makes up a large share of delivered cost or customers need service close at hand, which is the logic visible in the Knauf and Kingspan investments and in the float glass projects. Whether it holds for a particular product is a separate investment decision, discussed in our analysis of manufacturing in Ukraine. In cement, where output already exceeds domestic use, the CRH transaction shows acquisition used to expand a position rather than to import into it, and what such a deal secures is covered in our note on buying a company in Ukraine.
Some demand stays conditional, because it depends on 2026 priorities that are not funded, on reconstruction in occupied or front-line areas, or on permitted housing projects that have not started. For products tied mainly to those pools, the timing of any commitment rests on developments that current data cannot confirm, and testing a specific product against these conditions belongs to a structured market entry assessment rather than to national statistics.
What the evidence supports
Ukraine in September 2026 is a smaller physical market than the headline reconstruction figure implies and a more clearly mapped one than it was two years ago. Construction volumes stand around 40% below 2021 on the calculation above, and output fell by 11.2% in January to July 2026 while construction prices rose by more than a fifth. Builders name labour and finance rather than weak demand as the constraints on what they can execute. Materials demand within that market is concentrated in compensation-funded household repair, in protective works at energy sites, in a housing pipeline being completed from pre-war permits and in private logistics development.
Part of the identified demand is already funded or has progressed into active projects. The eRecovery programme has paid UAH 119.1bn, protective works worth UAH 24.3bn were tendered between March and mid-2026, and the Ukraine Investment Framework carries EUR 8.5bn of commitments. Knauf and Kingspan are building capacity, with a dry-mix line already producing in Borshchiv and the Lviv campus due mainly by 2030. Cement and, in normal conditions, long steel are supplied domestically, while float glass is not produced in the country at all.
Much of the remaining potential demand depends on funding, project delivery and broader economic conditions that have yet to be established. Two thirds of the government's 2026 priorities had no funding when the list was published, and the three float glass projects have raised only a small part of their budgets. RDNA5 projects economic growth of around 2% in 2026 if hostilities continue, rising to 4% in 2027 only if a ceasefire is in place by the end of 2026. The National Bank of Ukraine has since cut its 2026 forecast to 1.3% and expects 2.8% to 3.7% in 2027 and 2028 on the assumption that conditions normalise. Cement producers put their own investment threshold at domestic consumption of about 10m tonnes a year, roughly 60% above the 2024 level, which is a useful marker for when local capacity would start to tighten.
None of this evidence can establish the commercial prospects of a particular company’s product in Ukraine. National and sector evidence establishes activity, funding, domestic output, import dependence and the purchasing chain. It cannot show whether a particular product earns an adequate margin after freight and conformity work, whether Ukrainian designers and contractors will accept its specification, whether a named distributor can deliver the coverage it claims, or whether production here would outperform continued import. Those answers come from company-level and product-level testing, with sector context set out under Construction & Building Materials.