Wholesale trade produced the largest net increase in registered companies of any sector in Ukraine during the first half of 2026, adding 2,304 legal entities and comfortably outpacing IT and real estate. Candidate names are not scarce, and a separate reading of the same register shows how cheaply they can be produced, with 14 of Ukraine's most prolific serial founders having established 4,003 companies over four years, 30.7% of them in wholesale trade.
So a foreign principal begins with an abundant pool of uneven quality and, unlike in Poland or Romania, with a shrinking set of desk checks for telling one candidate from another. Most of the evidence a European commercial director would normally assemble before a first meeting has become harder to obtain since 2022, for reasons that have nothing to do with the companies being assessed.
Why the shortlist has to be built backwards from the customer
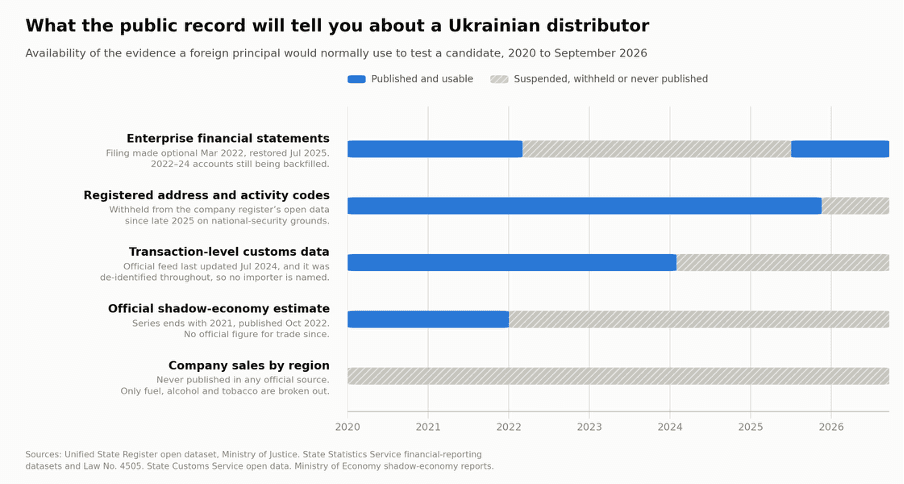
Ukraine's company register still confirms that a business exists, who signs for it and who is declared as its owner. It no longer publishes the registered address or the activity codes, both withheld from the open dataset on national-security grounds under martial law, so the register will not tell you where a candidate operates or what it says it does. Financial and statistical reporting was effectively optional between March 2022 and July 2025, when Law No. 4505 restored the obligation, which leaves accounts for 2022 to 2024 patchy and still being backfilled. The customs service's transaction-level open data was de-identified from the outset and last updated in July 2024, so it has never named an importer and no longer describes current trade.
Two things follow for the search itself, and the first is that directories and search results work poorly as a ranking device, because they surface companies that chose to be visible rather than companies that matter. The candidate universe is more reliably built backwards from the customer, by asking which operators already supply the chains, contractors, plants, clinics or dealers you intend to reach, and whose engineers those customers already see. Industry associations, sector trade events, existing manufacturer relationships and dealer networks identify participants in the relevant commercial ecosystem far better than any list. The second consequence is that the strongest remaining evidence now has to be bought or extracted rather than downloaded. Named import records by brand and volume are available commercially, though the provenance of that data is not transparent and it should be weighed accordingly. The court register remains free, public and updated daily, and it is the most revealing single source on a trading company, because it shows who has sued the candidate for unpaid invoices. Formal verification of ownership, sanctions exposure and authority to contract is a separate exercise that follows the shortlist rather than producing it.
Coverage has stopped being a statement about geography
Around a fifth of Ukraine's territory remains under Russian control, and the population that remains has not settled where the early war narrative implied. IOM's 2026 general population survey places the largest displaced populations in Dnipropetrovsk oblast, at roughly 611,000, and Kharkiv oblast, at roughly 469,000, ahead of Kyiv city and Kyiv oblast, with about 35% of all internally displaced people living in front-line districts. Demand has concentrated in the centre and east at least as much as it has moved west, and retail structure has shifted with it. National grocery chains kept expanding through 2025, but the sharpest growth came from regional operators, and the Lutsk-based Clever Stores group added 133 outlets to reach 443, overtaking Kyiv's Fora. Strong national-chain relationships do not automatically carry the regional ones that now move volume in particular oblasts.
The more consequential change is that physical reach has partly stopped being a distributor asset at all. Nova Poshta ended 2025 with 50,003 service points, a 32% increase in a year, and delivered 522 million parcels. A brand can now reach almost any Ukrainian settlement without a distributor's regional warehouses or delivery fleet, which erodes the moat that used to justify a national appointment on logistics grounds alone. What survives as genuine distributor value is trade marketing, shelf negotiation with the chains, product registration and certification, technical service and the willingness to extend credit to independent retail. Since no official source publishes company sales by oblast, claimed coverage can only be tested against the candidate's own records, which means sales by region over the last 24 months, the location of the field sales team and active rather than registered customer counts.
A good Ukrainian distributor is not a category
Concentration varies so widely by sector that the phrase carries little meaning until the product is specified. In pharmaceuticals two companies dominate, with BaDM and Optima-Pharm holding 45.7% and 38.9% of the wholesale market respectively in 2025. The Antimonopoly Committee fined the pair a combined UAH 4.8 billion in July 2025 after finding they had held more than 85% of the market and matched prices between 2020 and 2023. A principal entering that category is not running a selection process so much as negotiating with one of two counterparties, and should price the relationship on that basis.
Food and consumer goods distribution is considerably more fragmented and less transparent than the pharmaceutical market. Only one food company appears among Ukraine's ten largest wholesalers by revenue, a list otherwise made up of fuel, tobacco, pharmaceutical and metals traders, and no published market-share data for FMCG distribution exists at all. A shortlist in those categories has to be assembled from company-level financial statements rather than read off a ranking. This is why the required distributor profile has to be settled before the search begins. For a consumer brand dependent on retail access, assortment and sell-through, the test is chain and independent-trade relationships in named regions, whereas for industrial equipment it is technical selling, dealer relationships, spare parts and installation capability, which often sits with a much smaller company.
A sales forecast is a financing proposal
Ukrainian distributors fund inventory and customer credit at a cost European principals rarely have in mind. New hryvnia corporate loans carried an average rate of 15.3% a year in the second quarter of 2026, with foreign-owned private banks pricing lowest at about 13.5%. The National Bank raised its policy rate to 15.5% in July 2026 and signalled that easing is unlikely before the second quarter of 2027, with inflation expected to reach 10% by year end. Rail freight tariffs rose 30% on 1 August 2026 and a further 15% follows in January 2027, while warehouse vacancy in the Kyiv region has fallen to about 2.5%, leaving scattered units of around 1,000 square metres rather than usable blocks. Margin expectations that look high against Western European benchmarks may therefore be an accurate reading of what carrying stock in Ukraine actually costs.
Converting the candidate's forecast into the balance sheet it requires is the more revealing exercise, covering stock cover in weeks, credit extended to customers, the financing behind both and what happens to all three if volumes land materially below plan. Payment terms are also constrained by currency rules rather than by negotiation alone. Cross-border settlement for imported goods must complete within 180 days under martial-law rules, raised to 270 days for listed industrial equipment in September 2026, and any unsettled balance carries a penalty of 0.3% per day. Prepayment is permitted and the clock runs from the payment date, so the terms a principal would like to offer and the terms a distributor can safely accept are not always the same.
Market-share claims deserve particular care, because the denominator usually goes unstated. Analysis of filed revenue put the Rozetka group at 76% of the top ten online retailers' turnover for the first nine months of 2025. Rozetka's own founders put the group together with Prom at around half the market, arguing that a great deal of trade never reaches official reporting at all. The last official estimate of the shadow economy, published in 2022 for the year 2021, put unreported activity in wholesale and retail trade at 24% of the sector's value added, and nothing official has appeared since. Any share a candidate quotes is a claim about a denominator that nobody currently measures.
What appears strong | What must be established | Evidence that settles it | Decision implication |
National coverage | Whether sales actually occur in the claimed regions | Sales by oblast over 24 months, location of field staff, active customer counts | Price the appointment on demonstrated territory and treat the rest as unproven |
Warehouse capacity | What space is controlled today and on what terms | Leases and expiry dates, temperature zones, generator capacity, war-risk cover | Secured space is scarce, and space still to be arranged is a launch risk the principal absorbs |
Quoted market share | What the denominator is and who built it | Whether the figure rests on declared turnover or on an estimate of total trade | Treat a declared-turnover share as a floor rather than a measurement |
Sales forecast | The balance sheet the forecast requires | Stock cover, customer credit terms, financing source and cost | Test affordability before testing ambition |
Dedicated sales or service team | Whether those people are already employed | Named headcount, tenure, customers currently covered | Hiring commitments should not be valued as existing capability |
What the appointment commits you to
Naming the distributor as importer of record transfers considerably more than logistics. Under Ukrainian technical-regulation law the importer carries obligations close to the manufacturer's, has to retain the declaration of conformity for ten years, must place its own name and address on the product and becomes the addressee for consumer claims. Mutual recognition of conformity assessment with the EU is not yet in place either, because the ACAA agreement had still not been signed as of September 2026, with signature targeted for the end of the year and only three of 27 product categories covered in the first phase. Ukrainian conformity assessment and Ukrainian-language labelling therefore remain necessary, and both carry costs that belong in the launch case rather than in a later surprise.
Competition law works differently from the EU model that most European distribution templates assume. The Antimonopoly Committee's rules on vertical agreements exempt arrangements in which each party holds no more than 30% of the relevant market. Ukraine operates no self-assessment regime, however, so an agreement outside that safe harbour requires an actual permission rather than a reasoned internal file. Fixed and minimum resale prices are prohibited outright, while maximum and recommended prices are allowed. Restricting a distributor's active sales into another's territory is permitted, restricting passive sales is not, and fines reach 10% of turnover. The detail belongs with competition counsel and with our note on antitrust and merger control, but the commercial point is that exclusivity and territory clauses drafted for the EU do not transfer unexamined.
Exclusivity itself is an exchange rather than a concession needed to secure a partner. What the principal receives for restricting its own future options should be specific, covering stock commitment, dedicated resource, agreed investment, measurable performance and review points at which the arrangement can be reconsidered. Staged or conditional exclusivity handles this better than a general grant, although the drafting belongs with qualified legal counsel.
Commitment should follow evidence
A controlled pilot produces the kind of evidence that interviews and presentations cannot. A defined product range or territory, agreed reporting and pre-set criteria for stopping, adapting or scaling convert claims about customer access into observed sell-through, and the appropriate period follows the product's sales cycle rather than a standard term. Reporting on sell-through, stock on hand and customer-level movement is far easier to agree before the first order than afterwards, not least because a first order proves only that the distributor was willing to finance a position.
Given how much of the Ukrainian public record has closed since 2022, the appointment should rest on the few things that can still be established directly. Those are where the candidate already sells, what it already holds, who it already employs and how it finances the business it runs today, and the four answers together discriminate between candidates more reliably than any comparison of proposals. Whether a distributor-led route is the right structure at all is a prior question belonging to go-to-market design, and how coverage and channel architecture should be built out afterwards belongs to distribution strategy. Our market entry and expansion advisory work covers partner evaluation and shortlisting where an independent view is useful.