In July 2026 around 95% of Ukraine's non-agricultural exports left the country overland through the EU-Ukraine Solidarity Lanes, against roughly 5% by sea. Read as evidence that the land corridors have matured into a dependable route, that number misleads, because three months earlier the same series put the split at close to half and half. The July reading describes a maritime failure rather than a land-corridor capability, and a buyer who sized a continuity plan on it would have insured against the wrong thing.
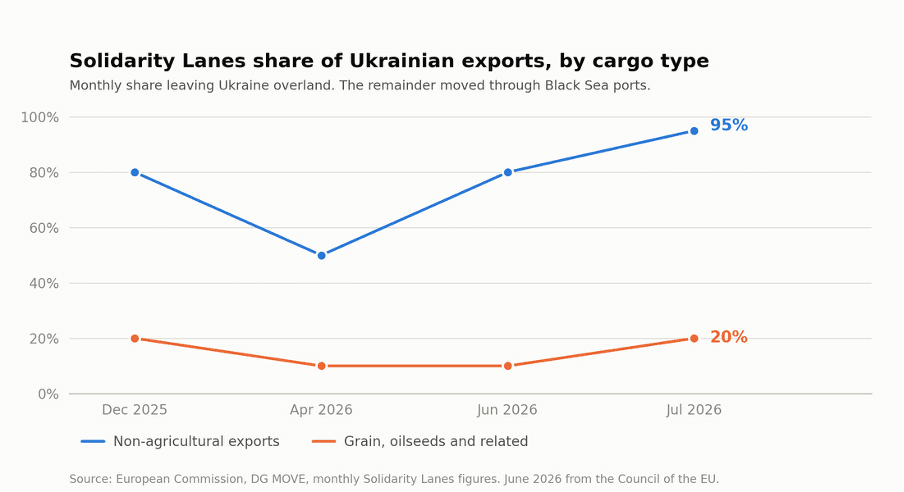
The chart also shows why a single Ukraine risk rating fails. Two cargo types, measured by the same institution on the same basis, run on separate systems and answer to separate shocks, so continuity depends on the weakest material dependency in one specific flow rather than on any national average.
Ukraine runs several logistics systems, and they price differently
The Commission's July 2026 figures showed grain, oilseeds and related products moving the other way, roughly 20% overland and 80% through Black Sea ports. Measured cumulatively since May 2022, of the roughly 255 million tonnes of grain, oilseeds and related products exported, the Solidarity Lanes carried 40% and the ports 60%. The divergence is economic rather than incidental, since bulk agricultural volume is maritime because no land mode approaches the cost per tonne of a deep-water vessel, while components and processed materials carry enough value per tonne to absorb rail or road economics.
Three 2026 policy changes now sit on top of that geography and move the landed cost of Ukrainian supply independently of any disruption. Ukrzaliznytsia raised freight tariffs by 30% from 1 August 2026, with a further 15% due on 1 January 2027, its first indexation since 2022. The EU carbon border adjustment mechanism entered its definitive phase on 1 January 2026. Because most Ukrainian producers are still priced on default emissions values rather than verified data, one assessment puts the cumulative export loss for 2026 and 2027 at about USD 1.4 billion, with iron and steel carrying 89% of it. From 1 July 2026 the EU steel safeguard also caps duty-free steel imports at 18.3 million tonnes a year and applies a 50% duty above quota. None of this is a transport problem, yet each item changes whether a Ukrainian supply line stays worth defending, so buyers in industrials and manufacturing should price them separately from disruption risk.
What the port shutdown revealed about substitution
Ukraine’s alternative export routes provide additional resilience, but their capacity differs substantially across the transport network. Ukraine's Ministry for Recovery, Infrastructure and Transport reported that seaports had handled 46 million tonnes by late July 2026, of which 42.2 million tonnes moved through the Greater Odesa cluster and 3.8 million tonnes through the Danube ports. Greater Odesa accounted for around 90% of Ukraine's agricultural exports. The Danube cluster, routinely described as the fallback, is about a tenth of the size of the system it was expected to replace.
When vessel calls at Greater Odesa stopped from 22 July 2026, that arithmetic appeared in the substitution rates within weeks.
Product | Moved by road, rail and Danube, early September 2026 | Share of the volume normal logistics would carry |
Grain | 380,000 tonnes | About 35% |
Oilseeds | 94,000 tonnes | About 60% |
Vegetable oil | 97,000 tonnes | About 66% |
Meal | 60,000 tonnes | About one third |
All agricultural products | 630,000 tonnes | About 40% |
The rail data underneath those totals is more instructive than the totals themselves. Grain shipped by rail to the Danube ports nearly tripled in August 2026 to about 248,800 tonnes, which sounds like a working alternative. Set against it, rail deliveries to the Greater Odesa ports fell by roughly 95% over the same period, from 1.44 million tonnes in July to about 317,300 tonnes in August. The backup absorbed a fraction of what the primary route lost. Substitution also follows the product rather than the corridor, since vegetable oil transfers onto rail tank wagons reasonably well while bulk grain does not, the constraint there being loading equipment, wagon availability and terminal throughput rather than track. Low summer water on the Danube then removed part of the barge option, with industry estimates putting Danube freight for Ukrainian iron ore around 70% above deep-sea rates.
The cost is already visible in national data, with the National Bank of Ukraine estimating that the logistics disruption will add 0.4 to 0.6 percentage points to annual inflation by the end of 2026, having raised its 2026 forecast from 9.4% to 10.0%. Buyers should expect suppliers to attempt to pass part of that through.
Failures do not travel in one direction
The standard mental model runs from supplier to transport to border to late delivery, but real disruption starts anywhere and propagates in both directions. Ferrexpo shows the pattern clearly. The company suspended iron ore production in Ukraine in early August 2026 after Black Sea shipping became unusable, partly to preserve working capital, then supplied European steelmakers from stockpiles until a recapitalisation of about USD 100 million let one pellet line restart on 7 September. Nothing had happened to the mine itself, because the logistics failure travelled upstream, stopped production and was absorbed downstream by inventory rather than by rerouting. That sequence is also why the company's balance sheet became a supply variable for its customers.
Rail is the dependency buyers most often underestimate, because it enters the plan as the solution and never as an exposure. Ukrzaliznytsia is a single national operator that carried 35 million tonnes of export freight in the first half of 2026, 47% of its total volume, and moves around 68% of Ukraine's grain exports. Ukrainian authorities recorded 1,534 attacks on railway infrastructure between January and late August 2026, with 492 locomotives damaged since February 2022 and the figure raised to 509 in early September. Rail is simultaneously the substitute for lost maritime capacity and a system under direct attack, so the two routes are not independent.
Power belongs in the same category, and the regulatory threshold is the most useful proxy available. Under Cabinet of Ministers Resolution No. 1041 of 19 August 2026, industrial and commercial consumers escape electricity restriction measures only where they cover at least 80% of consumption from own generation, distributed generation within one distribution system operator's area, or imports. A supplier below that line stays on the outage schedule whatever its generator nameplate suggests, because a set sized for refrigeration, lighting and process control is not the set that runs a line at rated output. Facility-level resilience design belongs with energy security and resilience planning, while a buyer's question is narrower and concerns whether the supplier's arrangement preserves committed output. Labour works more quietly and can cut output while transport runs normally, with the Institute for Economic Research and Policy Consultingfinding in July 2026 that 73% of surveyed firms faced a worker shortage and 79% named mobilisation as the main cause.
Failure layer | What interrupts supply | What reveals the real exposure | Continuity response that fits |
Supplier production | Damage, equipment failure, single line or single site, maintenance backlog | Whether the specified item can be made anywhere else with the same tooling and approvals | Qualified second site, tooling ownership, transferable specification |
Power and workforce | Restriction schedules, generator fuel supply, mobilisation, skills loss | Output actually achieved during the last restriction period, not installed generator capacity | Verified autonomy level, production prioritisation, output-based commitments |
Critical inputs and sub-suppliers | Imported material, specialised consumables, packaging, single-origin inputs | Whether the supplier's own inventory and input lead times are known or merely assumed | Input mapping, supplier-held buffer, approved substitute materials |
Domestic transport to port or border | Wagon and locomotive availability, damaged junctions, restrictions on named stations | Whether the cargo can physically reach more than one loading point | Second loading point, road leg for part of the volume |
Border crossing and transhipment | Gauge change, terminal and crane capacity, congestion, inspection throughput, transit priority rules | Which single node the whole volume passes through | Second crossing already used at low volume, intermodal option |
Maritime route and port access | Vessel availability, insurance withdrawal, terminal damage, draught limits | Whether the product has any economically viable land route at all | Inventory positioned outside Ukraine, contracted land allocation |
EU-side warehousing and onward flow | Customer-approved storage, handling capacity, onward haulage, quota and duty treatment | Whether the receiving side can absorb an irregular arrival pattern | Second approved warehouse, buffer nearer the buyer |
Finding the constraint that actually decides delivery
The binding constraint often sits within the production chain rather than the transport network. For a manufacturer of machined components the limit is frequently a single heat-treatment or coating subcontractor, with no corridor involved at all, while for a food processor it can be a customer-approved cold store.
Locating it takes a physical map of the flow rather than the commercial chart of who invoices whom. A working map records each leg and mode, every transfer point, the specific border node or berth used, the named carriers and terminal operators, realistic transit time with its observed variability, and the practical alternative at each step. Two features matter more than completeness. The first is any node that appears twice, because that is where diversification is nominal, and the second is any alternative that has never carried volume, since an untested route is an assumption rather than a capability.
The main difficulty is the limited availability of comparable data at the level of individual logistics nodes. Corridor-level statistics are abundant, while there is no published comparable series for dwell times at individual crossings and no public register of terminal capacity by node. The numbers that decide a specific chain therefore have to be collected from carriers, terminal operators and the supplier, then checked against observed performance over several months. That collection work is where most of the effort actually sits.
Two suppliers, one dependency
Dual sourcing protects against supplier-specific failure and very little else. Two Ukrainian suppliers commonly share a sub-supplier, an imported input, a rail crossing, a specialist carrier, a customer-approved warehouse or the same certification body, and if both depend on the same berth then one maritime interruption removes both. Supplier redundancy is cheap to arrange and easy to present internally, whereas dependency redundancy means finding the shared nodes and deliberately separating at least one, which takes longer and costs more.
The Moldova rail corridor to Constanța shows how far apparent redundancy can sit from executable redundancy. Ukraine and Moldova agreed a 50% discount on transit rail tariffs running to the end of 2026, and Ukrzaliznytsia considers it realistic to lift the corridor to 4.5 million tonnes a year. Yet Moldovan railways reserve their own grain wagons for local customers, so Ukrainian transit moves in Ukrainian wagons and competes for dispatch priority at the crossing. A route can be politically agreed, tariff-discounted and still throttled by an allocation rule at one station, which is the difference between a route that exists and a route a buyer can use. The same test applies everywhere, covering whether the product suits the mode, whether capacity is available at the required volume, and whether the receiving customer accepts the resulting handling.
Continuity measure | Failure it mitigates | Where protection stops | Principal cost or new dependency |
Parallel source outside Ukraine | Country-level, supplier-level and corridor-level interruption | Only holds where the second source is genuinely qualified and kept in production | Qualification and audit cost, volume split raises unit price, engineering time |
Buffer stock | Short interruptions of known duration, and lead-time variability | Fails the moment the interruption outlasts the cover held | Working capital, storage, obsolescence and shelf-life exposure |
Reserved capacity or shipment priority | Competition for scarce output or space when several customers are hit together | Worth nothing without demonstrated ability to allocate under stress | Premium or committed volume, weaker position on price |
Transferable production | Loss of one manufacturing site | Blocked by tooling, technical files, approvals, certification and ramp-up time | Duplicate tooling, requalification, customer re-approval |
Alternative routing | Failure of one node, corridor or mode | No protection where routes share an upstream node or where transit priority is allocated to others | Higher freight rate, longer transit, additional handling |
Alternative inventory location | Interruption between the supplier and the buyer's region | No protection if the stock still sits inside the disrupted geography | Warehouse cost, duplicated handling, reduced flexibility |
Inventory, priority and the limits of insurance
Buffer stock is the measure most often chosen and least often sized. The governing variable is the length of interruption the company intends to absorb, since four weeks of cover against a twelve-week disruption moves the date of the problem rather than the outcome. Ukrainian evidence now points to longer assumptions than most plans carry, because the 2026 shutdown of Greater Odesa had run for more than seven weeks by mid-September, with trade bodies advising members to plan on deep-water ports staying unavailable into December. That duration then interacts with replenishment lead time, product value, carrying cost, shelf life and the cost of downtime at the buyer's own plant.
Where buffer stock is held determines which disruptions it can actually protect against. Inventory held at the supplier covers only production interruption. Elsewhere in Ukraine, it remains exposed to the same corridor risk, while inventory near the border still depends on a single crossing. Only inventory positioned inside the EU or at the buyer’s site is genuinely insulated from a Ukrainian interruption, although it carries the highest working capital cost.
Available insurance mechanisms cover only part of the supply chain exposure a foreign buyer may face. Ukraine operates a state compensation scheme for vessel damage alongside the Unity facility underwritten through Marsh and Lloyd's syndicates, and further ship-insurance mechanismswere under discussion with the government in September 2026. Cover still does not span the whole export chain, and none of it compensates a buyer for a production stoppage caused by a missed delivery. Reserved capacity deserves the same scepticism, since a clause granting priority is not evidence of capability, and the question worth asking is how the supplier allocated output the last time several customers were hit at once.
Testing the plan and documenting what remains
A continuity document is not evidence that continuity will work, and credibility comes from specificity. A plan worth relying on names its failure scenarios individually, identifies alternative production arrangements with stated technical compatibility, reports autonomy measured during actual outages, maps critical inputs with real lead times, and commits to a recovery-time assumption the supplier will defend in writing. Evidence of how that supplier behaved through the 2026 port shutdown now outweighs all of it, since most Ukrainian exporters have just been tested in public.
The commercial operating layer needs the same discipline, so notification triggers, escalation routes, access to continuity information, shipment priority, inventory visibility and recovery reporting all have to be agreed before they are needed. Contractual drafting, enforceability and the interpretation of force majeure should be settled with qualified legal counsel.
Customers and procurement committees increasingly ask for supply-chain transparency, and generic reassurance fails that test. A defensible representation separates exposure, meaning which products and volumes depend on which Ukrainian nodes, from mitigation, meaning what is in place and has been tested, from residual risk, meaning the interruption length that would still cause failure. Adding the contingency option and its activation time completes it. This is a different exercise from planning the continuity of a company's own Ukrainian operation, which is a crisis management questionrather than a buyer-side one.
What has improved structurally, and what has not
Several changes to Ukraine’s transport infrastructure and its integration with the EU are now structural rather than temporary. Ukraine and Moldova joined the trans-European transport network in 2024, and the EU has mobilised more than EUR 2.3 billion for the Solidarity Lanes, including EUR 1.55 billion in non-reimbursable Connecting Europe Facility grants, which have leveraged more than EUR 2.9 billion of investment across 38 transport projects. Delivered assets include the relocated train inspection point at Mostyska II, opened in January 2025 under a EUR 65 million project, and Ukraine's first standard-gauge railway line, the 22 kilometres between Chop and Uzhhorod, opened in September 2025. The trade framework has also settled, with the upgraded EU-Ukraine agreement in force since 29 October 2025 and the road transport agreement, which removes permit requirements for bilateral and transit haulage, extended in September 2025 and now running to at least March 2027.
Announced capacity is not delivered capacity, and the distinction decides planning assumptions. The standard-gauge network does not yet carry freight beyond Uzhhorod towards Lviv or Kovel, so the gauge change at most crossings remains a physical requirement through the rest of this decade. Compliance deadlines attached to the road agreement bite sooner, since Ukraine must implement provisions on operator repute, manager training and smart tachographs by the end of 2026, and freight vehicles newly registered since 1 July 2026 must already carry them. Geography is unchanged in any case, because bulk commodities still need deep water, the western crossings remain a narrow set of nodes, and rail remains one national operator under attack.
The practical conclusion for a foreign buyer is that the corridor mix will keep shifting and the binding constraint will keep moving between production, power, inputs and specific transfer nodes, so continuity has to be run as a monitored position rather than a fixed architecture. That is execution work rather than analysis, and it is where operations consulting and execution support earns its place, converting a dependency map into supplier interfaces, allocation agreements, inventory positions and reporting that catches a constraint moving before a delivery is missed.