Ukraine's sourcing advantage is real, narrower than its trade figures suggest, and being compressed from two directions at once. The categories in which Ukraine ships the most value to Europe are largely the ones a European manufacturer cannot easily add to an approved supply base. The band where the advantage is genuinely structural is much smaller, and product characteristics define it more precisely than the country does.
The clearest evidence sits in the period when price should have decided everything. From June 2022 to June 2025 the European Union suspended essentially all import duties, quotas and trade defence measures on Ukrainian goods. Three years of complete liberalisation on the Union's eastern border left EU goods imports from Ukraine at €21.7 billion in 2025, below the €24.1 billion recorded in 2021. Ukraine's share of extra-EU imports moved in the same direction early on, from 1.1% in 2021 to 1.0% in 2022, which removes the objection that the value figures merely track commodity prices.
Tariffs, in other words, were never the binding constraint on European buyers. What decides a Ukrainian sourcing case is the cost of qualifying and holding the supply, the shape of the category, and a regulatory environment that has moved sharply since 2025 in both Brussels and Kyiv. This analysis sets out where sourcing from Ukraine holds up for industrial and manufactured inputs, where the advantage disappears under total cost, and the conditions under which the correct answer is to decline.
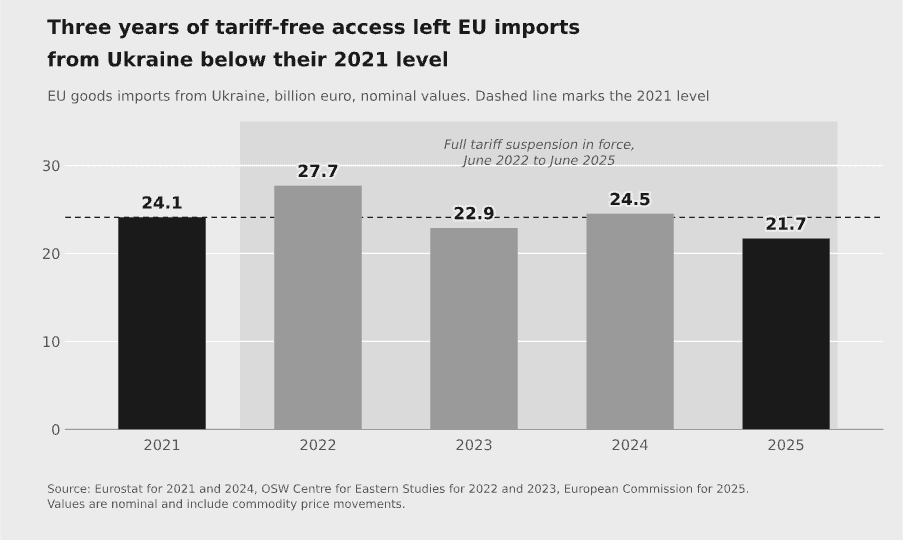
EU goods imports from Ukraine, 2021 to 2025. Values are nominal. Compiled from Eurostat, the OSW Centre for Eastern Studies and the European Commission.
What Ukraine sells to Europe is not what most industrial buyers are trying to source
The European Commission records Ukraine's principal goods exports to the EU by value as animal and vegetable fats and oils, cereals, iron and steel, oil seeds, and ores, slag and ash. Ukrainian customs data describe the same structure from the other side. Of $40.3 billion in goods exports in 2025, food products accounted for $22.5 billion, metals and metal products for $4.7 billion, and machinery, equipment and transport for $3.6 billion. Ukraine's own Export Strategy to 2030was approved by the Cabinet of Ministers in June 2026. On a broader measure that also captures services, it puts raw materials and goods with a low degree of processing at 87.3% of exports in the first nine months of 2025, and sets a target of 59% by 2030. The two measures are not directly comparable, but they point the same way.
That composition works as a filter on the sourcing question. Bulk agricultural commodities and semi-finished metals trade against specifications that already exist, on terms where supplier identity carries little weight and formal qualification barely applies. The segment a European industrial buyer would actually audit, trial and onboard is the machinery, equipment and transport line, and at $3.6 billion it is modest against the headline. Whether a requirement sits there or within agricultural and food supply changes almost every parameter of the decision that follows, which is why a country-level view of Ukrainian sourcing tends to mislead.
Where the conversion advantage is real, and why it is narrowing
Where Ukraine competes for manufactured work, conversion economics are the reason. Analysis by the OSW Centre for Eastern Studies, drawing on Ukrainian official statistics, found that in early 2026 the average Ukrainian wage stood at half the level of Poland's statutory minimum wage and nearly four times below the Polish average. That differential is the single most durable input into any Ukrainian sourcing case, and it is also closing. Average gross wages rose from UAH 14,600 in the first quarter of 2022 to UAH 28,300 in the fourth quarter of 2025, and in dollar terms from about $500 to $670. The National Bank of Ukraine expects real wages to rise by more than 12% in 2026 after 7% in 2025, with the pace slowing only once the labour shortage loosens.
The more consequential change is in what constrains a supplier. By March 2026, 67% of Ukrainian enterprises reported labour shortages as a business obstacle, ahead of workplace security at 42% and power or heating outages at 30%, with large firms reporting the problem most often at 76%. Availability, not price, now determines whether a Ukrainian supplier can absorb additional volume, and that has two practical consequences. A wage differential converts into a sourcing advantage only where labour forms a substantial share of conversion cost, which points towards assembly, harnessing, finishing and joinery and away from automated or capital-intensive processes. It also means a supplier quoting attractively on a small base may not hold that quotation when asked to double output, because the scarce input is the marginal worker and not the marginal machine hour.
Two EU instruments repriced Ukraine's largest industrial category
The most instructive recent development in Ukrainian sourcing did not originate in Ukraine. The Carbon Border Adjustment Mechanism entered its definitive phase on 1 January 2026, and the German Economic Team models a sector-average cost for Ukrainian iron and steel of $146.6 per tonne in 2026, rising to $178.6 in 2027. Its projection puts cumulative Ukrainian export losses to the EU at around $1.4 billion across 2026 and 2027 against the 2025 baseline, with iron and steel accounting for 89% of that total. These are modelled projections, not observed outcomes, and should be read as such.
The compliance infrastructure behind those numbers is still incomplete, which matters to any buyer whose category falls in scope. Ukrainian producers reported in April 2026 that no Ukrainian verifier was accredited within the EU emissions trading system and that calculation methodologies were still missing for several product categories. Where verified emissions data cannot be produced, importers fall back on default values set deliberately above typical actual emissions, so the gap converts directly into landed cost.
The second instrument compounds the first. Regulation (EU) 2026/1384 replaced the expiring steel safeguard from 1 July 2026, cutting duty-free import volumes by roughly 47% to 18.3 million tonnes a year and doubling the out-of-quota duty to 50%. The regime applies to imports from countries holding preferential agreements with the Union, and the Commission granted Ukraine a special status in the allocation to sustain a level of wartime exports, which softens the effect without removing the category from the regime. The wider point generalises beyond steel. In the category where Ukraine holds its clearest raw-material and installed-capacity advantage, the economics were altered by the buyer's own jurisdiction. Neither the supplier, the war nor the exchange rate moved them, and a trade agreement that removes tariffs leaves that class of exposure untouched.
What the upgraded DCFTA settles, and what it leaves with the buyer
The upgraded DCFTA entered into force on 29 October 2025, replacing the temporary autonomous trade measures with a permanent framework offering reciprocal liberalisation and alignment of production standards. Three features matter more to a procurement decision than the tariff schedule itself.
Predictability improved in form while remaining conditional in substance. Increases in tariff-rate quotas are tied to Ukraine's progressive alignment with EU production standards, assessed through annual progress reports, and the agreement carries a safeguard clause allowing measures where imports cause serious difficulties, including at the level of a single member state. The liberalised road access carrying much of this supply rests on a separate agreement extended only to 31 March 2027, renewed repeatedly since 2022. A buyer committing multi-year volume is therefore accepting a set of political variables, none of which is fixed.
Conformity assessment remains unresolved, and this is the item most often assumed away. The Agreement on Conformity Assessment and Acceptance of Industrial Products has not been concluded, its first round would cover three of twenty-seven product categories, and the Union has concluded only one such agreement to date, with Israel. Ukraine adopted the enabling legislation on accreditation and technical regulation in April 2026, which moves the process forward without concluding it. Until it is in force, a Ukrainian supplier's certification does not travel into the EU on its own authority and the qualification burden stays with the buyer.
The most undervalued element is origin. Ukraine is a contracting party to the pan-Euro-Mediterranean Convention, so Ukrainian inputs can contribute to originating status across the Union's wider preferential network. For a manufacturer that re-exports within that zone this is a structural advantage no non-PEM low-cost source can offer, and it is routinely missed because it sits with customs rather than with procurement. Where the origin arithmetic is material, specialist customs advice belongs before the sourcing decision, not after it.
The Ukrainian rules that shape the commercial terms
European buyers tend to research the EU side of this relationship and take the Ukrainian side on trust. Several domestic measures bear directly on what a Ukrainian supplier can agree to, and none of them is visible in a quotation.
Payment terms are capped by currency rules before negotiation begins. Ukrainian exporters must repatriate proceeds within deadlines set by the National Bank of Ukraine, with a general ceiling of 180 days. For listed grain and oilseed codes the National Bank cut that deadline to 90 days in November 2023 under Resolution 145, then raised it temporarily to 150 days in 2026. A supplier cannot lawfully accept terms that breach the applicable deadline, so a buyer expecting extended credit in those categories should establish the position before opening talks.
Ukrainian trade policy also pushes exporters up the processing chain, which changes what is available at what price. Ukraine applies a 10% export duty on sunflower seed and the agriculture ministry confirmed in September 2026 that removing it is not under consideration, the stated rationale being that processed product travels better than bulk seed. Bills 15522 and 15522-1 would temporarily cut oilseed export duties to zero but remain before parliament with industry associations divided, so the measure remains proposed and has not been adopted. A buyer comparing Ukrainian seed against Ukrainian oil is therefore comparing two different policy regimes.
Customs mechanics work in the buyer's favour more than most expect. Ukraine acceded to the Common Transit Convention on 1 October 2022, so consignments can move under a single transit declaration with electronic tracking, and traders registered as authorised consignors or consignees can despatch directly from their own premises. The Commission's own guidance notes that transit movements started inland usually clear the border faster because controls at the frontier are minimal.
Supplier-side risk cover is thinner than the existence of a state programme suggests. The war risk insurance scheme run by the Export Credit Agency was widened in 2026 to include production equipment alongside real estate, with compensation capped at UAH 10 million per legal entity. Against the replacement cost of an industrial line, that is a small figure, which means a supplier hit in a high-risk region is substantially self-insured and may not be able to rebuild on its own balance sheet. Assessing that exposure sits alongside the wider question of political and operational risk in Ukraine.
Where each measure currently stands
Measure | Status as of September 2026 |
Upgraded EU-Ukraine DCFTA | In force since 29 October 2025 |
CBAM definitive regime | In force since 1 January 2026 |
EU steel regulation 2026/1384 | Applies since 1 July 2026, Ukraine holds a special allocation status |
EU-Ukraine road transport agreement | In force until 31 March 2027 |
ACAA industrial conformity agreement | Not concluded, Ukrainian enabling law adopted April 2026 |
Ukrainian export duty on sunflower seed | In force at 10%, removal not under consideration |
Zero export duty on rapeseed and soy | Proposed, bills before parliament |
Ukrainian export proceeds deadline | 180 days generally, 150 days temporarily for listed agricultural codes |
Ukraine Export Strategy processing target | Announced government target for 2030 |
From quoted price to decision cost
A supplier quotation is the smallest component of a Ukrainian sourcing decision and the only one visible at the outset. No public landed-cost benchmark exists for Ukrainian supply by category, and none was found in the sources reviewed for this analysis, so the figures have to be built from a buyer's own category data. The components that most often decide the case are these.
Inbound logistics. Road dominates the flow to Central Europe, with 7.7 million tonnes worth €10.1 billion moving by road in 2024. Test delivered cost per unit, not per consignment, and include border dwell time. Freight that consumes more than the conversion saving disqualifies the category immediately.
Trade treatment. Broad liberalisation under the DCFTA coexists with product-specific quotas, safeguards and carbon exposure. Establish what the specific commodity code carries, since a quota that closes mid-year changes the economics without warning.
Qualification, audit and testing. These are fixed costs incurred once per supplier and per category, and mutual recognition does not yet reduce them. The right measure is total internal and external cost to first approved delivery, which is why addressable annual spend decides more cases than the percentage saving does.
Internal engineering and quality time. This is frequently the largest unbudgeted item in the case. Count the hours the technical function will actually commit and cost them at loaded rates, because a category that needs engineering presence the buyer cannot spare will fail regardless of price.
Buffer stock and second sourcing. Both are usually higher than for an equivalent intra-EU source and both are rarely optional. Price the buffer the risk committee will actually require, and check whether the alternative source will hold its price once volume moves away from it.
Customer approval and traceability. A buyer's own customers may constrain an origin change. Where an automotive, aerospace, defence or food customer has to re-approve, the timetable belongs in the business case and not in the implementation plan.
Concentration and qualification decide more cases than price
Concentration and qualification can both be settled before any supplier is named. On concentration, the test is whether the category can be transferred at all. In 2022 the closure of wire-harness plants in western Ukraine interrupted assembly at Volkswagen, BMW and Porsche within days, because harnesses are configured per vehicle and cannot be reassigned quickly. Transferability of specification, the availability of alternative capacity and the size of the buffer a buyer would have to hold are category questions that belong to the sourcing decision itself.
On qualification the arithmetic is straightforward and frequently ignored. Audit, testing, production trials, documentation, quality-system alignment and internal engineering time behave as fixed entry costs, so the same percentage saving that comfortably absorbs them at high annual spend cannot absorb them at low annual spend. Ukrainian sourcing cases fail on that arithmetic more often than they fail on risk.
A pilot is where the remaining uncertainty gets priced. Ordering a modest quantity and watching what happens produces reassurance without producing information. A pilot worth running fixes one product family, a defined commercial exposure, an explicit specification, measurable quality and delivery requirements, a named internal resource commitment and stop-or-scale criteria agreed before the first order. It should establish whether the quoted economics survive actual delivery, whether quality is repeatable and not merely achievable once, whether corrective action functions under pressure, and whether the management burden is acceptable at scale.
When the answer should be no
Declining is frequently the correct decision, and the disqualifying conditions are recognisable in advance. A price advantage too thin for total cost to absorb, a qualification cost disproportionate to addressable spend, or a downstream customer whose approval is tied to existing sources will each end the case on its own. Energy and carbon-intensive categories warrant particular scepticism, because the instruments governing them are tightening rather than relaxing. So do categories with no alternative Ukrainian capacity, where the buffer needed to make the exposure tolerable consumes the saving, and categories whose specification changes often enough to require engineering presence the buyer cannot sustain.
One case is misread more often than the others and deserves naming. A discount that exists only because a supplier is pricing against depressed domestic demand and temporary spare capacity is a price opportunity, and both of those conditions reverse when demand returns. Reading that as a structural cost advantage is the most expensive mistake available in this market, because it commits qualification spend against a saving that will not last.
What could change the proposition by 2030
Three developments would strengthen the case. Conclusion of the conformity assessment agreement would remove a measurable qualification cost. Demobilisation would release a substantial labour pool, with roughly a million people currently under arms and a government reintegration strategy contemplating the return of up to two million more, although the timing and scale of both are unknowable from present evidence. Continued regulatory alignment would reduce the documentation friction that makes Ukrainian supply administratively expensive to run.
Working in the other direction are wage convergence, reconstruction demand competing for the same industrial capacity, and the trajectory of EU carbon and trade instruments. Taken together these forces point towards Ukrainian suppliers becoming easier to use and simultaneously more expensive, since the alignment that lowers the cost of qualifying a supplier also raises that supplier's own compliance costs, and the labour recovery that frees capacity raises its price. A buyer waiting for conditions to become comfortable may find the differential has narrowed by the time they act.
The decision principle is therefore narrower than the country question implies. Ukraine earns a place in a European supply base where the category is labour-intensive in conversion, tolerable in value-to-weight, light in regulatory burden, transferable between producers, and large enough in annual spend to absorb a real qualification cost. Those conditions describe a structural advantage that should persist in some form through the decade. Where they are absent, a favourable quotation is evidence about one supplier's current capacity position and nothing more, which is a distinction worth establishing before any volume is committed. Carrying that judgement through to qualification, onboarding and supplier management is the work of operations consulting and execution support, and buyers approaching Ukraine for the first time will find the wider context in our guide to doing business in Ukraine.
If you are weighing whether Ukrainian suppliers belong in your category strategy, speak to a senior adviser before committing qualification spend.