Ukraine’s transaction record confirms that selling an operating business remains a viable route for owners. The longest continuous count of the market registered 63 deals above USD 5 million in 2025, against 75 in 2021 and 29 in 2022, and the first half of 2026 ran ahead of the first half of 2025. What the same record cannot establish is the saleability, the value, the realistic buyer universe or the usable proceeds of any particular subsidiary, and that gap is where the ownership decision actually sits.
For a foreign shareholder or parent that no longer clearly wants its Ukrainian business, the choice runs between selling it, keeping a smaller or redesigned operation and closing it. National evidence describes the environment around that choice and stops at the perimeter of the company. It shows how many deals complete, who is buying, how long approvals take and on what terms money can leave the country. Around four in ten of the deals recorded in 2025 carried no published value, three transactions accounted for roughly half of the value that was disclosed, and no Ukrainian dataset identifies the nationality of the seller.
The limits of public evidence do not prevent an owner from assessing the available options. They mark out which questions can be settled from public Ukrainian sources, among them ownership chains, audited accounts, procurement and customs records, approval timetables and payment routes, and which have to be answered from inside the business.
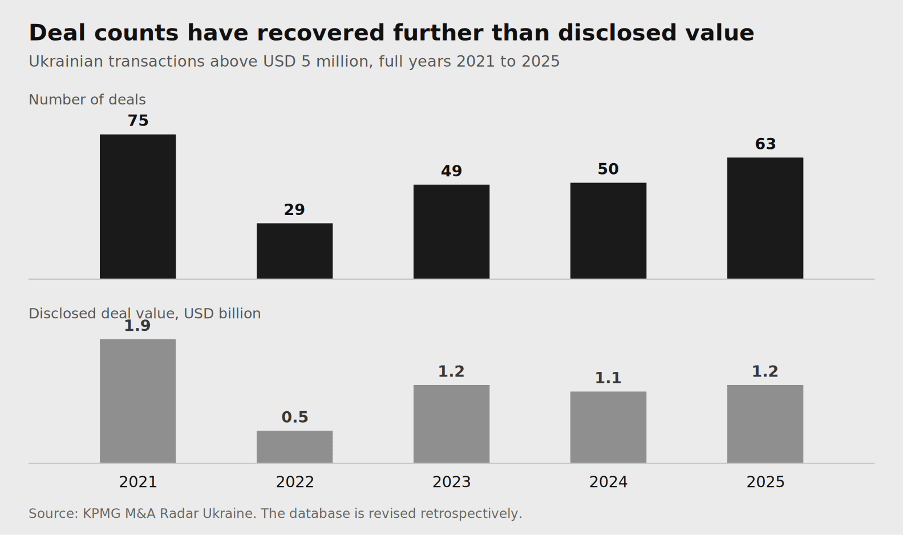
Ukrainian transactions above USD 5 million and their disclosed value, from KPMG's M&A Radar.
Deal flow has recovered faster than price evidence
Ukraine’s transaction market has recovered progressively since the sharp contraction in 2022. More than 20 deals announced in 2021 were cancelled the following year, when disclosed value fell to about a quarter of its 2021 level. Counts have risen in every year since, and by 2025 they stood at roughly four fifths of the 2021 figure while disclosed value remained under two thirds of it. That comparison comes from KPMG's own series rather than from any published index of Ukrainian deal prices.
Half-year readings are provisional, which matters whenever a decision is timed against them. KPMG first reported the first half of 2025 as 34 deals worth USD 716 million, and in its July 2026 edition the same six months read as 35 deals worth USD 1,029 million. Price visibility behaves the same way and improves as values emerge.
Period | Deals with a published value |
2024 | 64% |
2025 | 57% |
First half of 2025, as first reported | 50% |
First half of 2025, as later restated | 63% |
First half of 2026, as first reported | 45% |
Source: UA Consulting analysis based on M&A data.
Read in that light, the apparent slide in disclosure says less than it appears to. A first reading of 45% belongs beside the first reading of 50% a year earlier rather than beside a matured 63%, and KPMG expects visibility for 2026 to improve as the year closes. The longer record sets a lower ceiling in any case, because no value was published for 54% of known Ukrainian deals between 2013 and 2025.
Published values also mix amounts released by the parties with market estimates. KPMG records PZU's pending purchase of MetLife Ukraine at about USD 100 million although neither company has disclosed a price, and an insurance trade publication has cited a higher estimate. Sampling differs too. A study by the law firm Aequo and Forbes Ukraine, which counts only deals of at least USD 5 million where the buyer takes at least 10% and models values where none is published, recorded 41 transactions in 2025 rather than 63. The two sources do not even agree on who is buying, with KPMG classifying 63% of its first-half 2026 deals as domestic against 26% in the Aequo sample for January to May.
Available transaction data does not show how many foreign owners have sold their Ukrainian businesses. Transactions are classified by the location of the buyer and the target rather than the seller, meaning that a foreign parent selling a Ukrainian subsidiary to a Ukrainian buyer is recorded as a domestic transaction. The pace of foreign exits therefore cannot be established from these statistics.
The buyer universe is narrower than the deal count suggests
Ukrainian buyers have accounted for the majority of transactions by number in every period since 2023, while foreign buyers accounted for more than half of disclosed value in 2024 before their disclosed value fell by 59% in 2025. Inbound deals then doubled to ten in the first half of 2026 and disclosed inbound value rose from USD 26 million to USD 415 million, driven largely by an edtech funding round and PZU's agreement. KPMG treats the change as a possible early signal rather than a confirmed recovery, and a base of five deals a year earlier makes the percentage movement look larger than the underlying shift.
Part of the strength in domestic dealmaking reflects the regulatory environment. Restrictions on capital outflows have reinforced the relative position of domestic buyers in the transaction market. The Aequo study traces the same mechanism through large companies that could not pay dividends abroad and accumulated hryvnia instead, with Kyivstar's cash rising twelvefold over three years before a run of acquisitions. An investment banker interviewed for the same review described the most active buyers as those holding hryvnia liquidity and willing to settle inside Ukraine, while owners of strong businesses resist being paid in hryvnia.
Foreign buyers that do commit tend to arrive with a specific reason to own a particular asset. Bunge raised its 15% stakein the ViOil oilseed plant to full ownership in 2025, the largest inbound deal of the year, and PZU, already operating in Ukraine, pointed to a complementary sales network and client base. The consortium that bought lifecell from Turkcell came with EBRD and IFC debt, according to Horizon Capital's account in KPMG's 2025 review. Existing co-owners, or managers through a management buyout, form a further group where the purchase can be funded. The realistic field for any seller is therefore defined less by the size of the market than by who has a reason to own this particular business, a question examined from the buyer's side in buying a company in Ukraine.
Regulatory requirements can materially affect both the buyer universe and the timetable for completing a transaction. Clearance from the Antimonopoly Committee is required under Article 24 of the competition law once the parties' combined worldwide assets or turnover exceed EUR 30 million and at least two of them each exceed EUR 4 million in Ukraine. A second threshold catches deals where the Ukrainian side exceeds EUR 8 million and another party turns over more than EUR 150 million worldwide. The test runs on the combined size of the parties, so a mid-sized Ukrainian subsidiary sold to a large group still needs clearance. The Aequo study puts simplified review at up to 25 days and standard review at up to 45 days once a filing is accepted, while a complex case can add at least three months. Ownership, sources of funds and sanctions exposure now receive close attention. The same study observes that the bidder with the most credible route to closing frequently prevails over the highest offer, which turns merger control from a closing formality into a factor in how a seller compares bids.
The sale of Idea Bank illustrates how these pressures can converge, with its Polish owner, Getin Holding, agreeing to sell the bank to a Ukrainian lender in November 2021 before the agreement was terminated in February 2022. After the NBU gave Getin six months to divest, the owner signed in October 2024 with a Cyprus company owned by the Ukrainian businessman Serhiy Tigipko. The base price was USD 34 million, with a further USD 0.8 million due for each full month that completion slipped beyond 2024. Clearance came in December, the NBU extended its own review twice, and the bank changed hands in April 2025 for USD 36.5 million. KPMG lists the buyer as Ukrainian, so a Polish owner's exit sits among the domestic deals in its data.
Completing a sale and moving the proceeds are separate questions
Much of this pattern traces back to the currency regime. On 24 February 2022 the NBU fixed the exchange rate and imposed controls under which cross-border transfers are prohibited unless expressly permitted. The central bank has described those decisions as temporary measures that prevented panic and kept the financial system working. In mid-2023 it adopted a three-stage strategy for unwinding them, with no dates attached and each step conditional on inflation, reserves and financial stability, and in October 2023 the hryvnia moved to managed flexibility.
Easing for business has since come in packages, each with a stated purpose. In May 2024 companies were allowed to send abroad dividends on profits earned from 2024, up to EUR 1 million a month, a step the NBU said would support new investment and reduce the risk of foreign-owned companies winding down. A year later it introduced incentive limits that let companies exceed the general caps up to the amount of new foreign equity they attract. In August 2025 eligible profits were extended back to 2023 with the cap unchanged, and a further limit was tied to donations for the armed forces. Governor Andriy Pyshnyi presented the dividend change as giving companies that stay in Ukraine access to at least part of their profits. Limits based on new foreign loans followed in January 2026 and limits based on direct charitable donations to military units in August 2026.
The incentive limits unlock a defined list of transactions, and the NBU's August 2026 package confirmed that the list has not changed. It covers dividends, payment for old imports, refunds of pre-invasion prepayments, repayment of old external loans and funding of foreign offices. Neither the proceeds of selling a business nor the return of invested capital appears on it, and the NBU's strategy leaves repayment of investments to its final stage. Kinstellar's summary for AmCham Ukraine sets out the practical consequence under the regime as it stands. A foreign seller paid in Ukraine by a domestic buyer may hold the money in the country but may not transfer it abroad, whereas a price settled abroad between non-residents falls outside these particular rules. Both positions depend on the structure of the transaction and on the exceptions available at the time, so each needs to be confirmed with Ukrainian counsel rather than assumed.
A completed transaction shows what payment location means in practice. When Kyivstar acquired the pharmacy platform Tabletki.ua in February 2026, VEON disclosed a consideration of USD 160 million payable in hryvnia inside Ukraine. The seller in that case was Ukrainian, but the currency and the location of payment are the same constraint a foreign owner meets whenever the credible buyer is domestic.
An owner preparing to sell a Ukrainian business therefore faces three distinct questions, about whether the deal can complete, how and where the consideration is paid, and whether the parent can use the money where it needs it. Sellers adapted to the second of these early, and KPMG's 2023 review reported a sharp rise in deals for Ukrainian targets structured through foreign jurisdictions, with sellers using foreign companies and bank accounts to receive payment in foreign currency. The investment banker interviewed a year later described parties agreeing a price quickly and then negotiating at length over how much would be paid inside Ukraine and how much outside. A lower price settled abroad can therefore be worth more to a parent than a higher one that has to stay in the country, which follows from the payment rules rather than from any published deal data.
The dividend route has become a genuine channel, though a much narrower one than before the invasion. The NBU told Ekonomichna Pravda that companies sent USD 1.6 billion in dividends abroad between mid-May and the end of 2024 and a further USD 1.7 billion between January and early August 2025. An NBU deputy governor put repatriated dividends at USD 7.5 billion for the first eleven months of 2021. By February 2026, Pyshnyi said, nearly 1,000 companies had used the dividend route, while the investment limit had been drawn on for only USD 25 million.
Saleability depends on what survives separation from the parent
Whether a particular business can be sold depends on its own economics, operating model and ability to function independently of its current owner. That depends on evidence only the company holds, much of it concerning what the operation would be without its current owner. A subsidiary can look healthy inside a group because the parent finances it, buys for it, runs its systems, guarantees its obligations, lends it a brand or sends it customers. Selling a Ukrainian company built that way asks a buyer to value it once those supports are withdrawn or replaced, so the transferability of its earnings matters as much as their level.
A buyer therefore tests what the parent has been supplying and what would have to be replaced, along with title to key assets, licences and material contracts, dependence on a few customers, suppliers or managers, related-party arrangements and unresolved compliance matters. Each uncertainty left open tends to return as a lower price, a larger deferred payment or a thinner field of bidders.
What can be verified in Ukraine, and what cannot
Much of what a buyer will check is already public, and a seller who has not read it is negotiating blind. Under Article 14 of the accounting law financial statements are not a trade secret, public-interest entities publish audited annual accounts by 30 April, and large and medium companies publish theirs by 1 June. Ownership data became easier to pull in January 2026, when the Ministry of Justice restored open-data publication of the company register under the wartime access law, with defence-sector and strategic entities filtered out. Around those two sources sit the court decisions register, tax debt and enforcement records, licence registers, sanctions lists and the Antimonopoly Committee's own decisions.
Operating claims can be tested against independent trails. Sales to the state and to state-owned companies appear in the public procurement record, import and export flows appear in customs data, land banks and lease rights appear in the cadastre, and regulated activities appear in sector registers. For a subsidiary whose management reports durable customers or full capacity, that comparison is usually where the story either holds or does not.
Three Ukrainian specifics deserve particular attention, because buyers price them. Staffing is the first of them, since an enterprise recognised as critically important may reserve up to 50% of its employees liable for mobilisation, and up to 100% in defence, energy and frontline areas. Enterprises holding that status had to re-confirm it during 2026 or lose the right to book. Whether the target still holds the status, and whether it covers the people the business depends on, is a question about operating continuity rather than paperwork. Physical exposure sits alongside it, including location relative to the front, energy resilience and the insurance actually in place on key assets. Ownership and sanctions chains on both sides complete the list, and the Aequo study reports that buyers now check them before serious negotiation begins.
Reliable market benchmarks for valuing individual Ukrainian businesses are not publicly available. No register records transaction prices, no published series tracks Ukrainian multiples by sector, no dataset counts distressed sales, and the deal trackers record neither the seller nor the reason for the sale. Only a handful of Ukrainian groups are listed abroad, so quoted comparables cover a narrow slice of the economy and none of the typical mid-sized subsidiary. Verification effort therefore belongs where evidence exists, on ownership, obligations, customers, assets and people, while price has to be argued from the company's own numbers rather than from a market benchmark.
Preparation determines how clearly a buyer can assess the business and how efficiently the sale process can proceed. Smaller Ukrainian targets often report under national accounting standards with limited detail, so the work usually starts by turning statutory accounts into an earnings picture a buyer can test. It continues by assembling the register, procurement, customs and court evidence before a buyer finds it, and by separating what belongs to the parent from what belongs to the business. Mapping the buyers with a reason to own the asset and setting out the approval path and the payment route come next. KPMG reports growing use of vendor assistance and vendor due diligence, both rare in Ukraine until recently. Horizon Capital told KPMG that it is preparing a number of holdings for sale through equity stories, vendor due diligence and early talks with likely buyers, while avoiding forced sales.
No published benchmark prices an individual business
Preparation narrows the uncertainty around price without removing it, because the published evidence offers no benchmark. It supports neither a standard Ukrainian valuation multiple nor a measurable country or war discount. Wider availability of war-risk insurance has been associated with lower valuation discounts, while market evidence also indicates that some quality assets have been acquired without discounts, although neither observation is supported by published valuation data. Where differences are described they follow the exposure of the asset, and InVenture's review of farmland deals reports that assets in frontline and near-frontline regions sold at larger discounts or after longer negotiation, while demand in central and western Ukraine stayed strong.
Two rational parties can therefore reach different values for the same business for reasons that have nothing to do with negotiating tactics. They may take different views of future cash flow and of how much of the earnings will survive a change of owner, and they may disagree on management continuity, capital expenditure, separation costs, customer durability and what exposure to Ukraine costs them. A buyer that already operates in the country, can insure war and transfer risk or holds hryvnia it cannot otherwise use may carry those risks more cheaply than the seller. That gap has been visible in the Ukrainian market, with buyers seeking war-related discounts while sellers have often resisted them, partly because restrictions on capital outflows reduce the alternatives for deploying sale proceeds.
The pending sale of MetLife Ukraine illustrates the point without revealing the price. The insurer led its market with close to half of all life premiums, was consistently profitable and had secured approval to pay dividends of up to EUR 1 million a month. PZU told its investors that the pro forma dividend yield would exceed its own even after the limits on dividends from Ukraine, and that KUKE, Poland's export credit agency, insured it against war, expropriation and transfer risks. MetLife recorded a USD 65 million after-tax impairment on the sale. That loss is not evidence of a Ukrainian discount, since the group also booked losses when it sold its Argentinian business in 2021 and its Polish and Greek businesses in 2022.
Where a valuation gap cannot be closed on price, transaction structure can provide an alternative means of allocating risk between buyer and seller. Completion accounts, deferred consideration, earn-outs and call options have all become more prominent in Ukrainian transactions. Turkcell’s exit followed part of that pattern. Turkcell's exit followed part of that pattern. It received USD 524.3 million when the sale of lifecell and two related companies completed in September 2024, and the final price of USD 538.7 million was set in August 2025 after adjustments for cash and debt.
Continued seller involvement offers another bridge. When the Ukrainian co-founder of Modern Expo agreed in 2025 to buy out his Polish partner, ownership was set to pass in stages through annual payments over several years, with the seller remaining a passive shareholder in the meantime. Horizon Capital took a different route when NJJ acquired Datagroup-Volia, rolling part of its equity into the combined business. Their drafting and enforceability are matters for legal advisers.
The public record rarely explains why owners sold
Transaction records establish that ownership changed, but they seldom explain why. Turkcell gave no reason when it announced the lifecell agreement at the end of 2023, and MetLife has published none for Ukraine, although the group has sold businesses in several other countries since 2021. Idea Bank is the exception, because the regulator's requirement to divest is on the record. In the Modern Expo case the explanation came from the buyer, who described partners with different plans and different succession prospects. Reading a war-driven retreat into every foreign disposal, or into none of them, goes beyond what the record shows.
The same discipline applies inside the owner's own organisation. A review prompted by weak results has to separate structural economics from temporary pressure, execution problems, management capability and a simple loss of attention at headquarters before it concludes that ownership itself is the problem. That diagnosis is a separate exercise, covered in assessing an underperforming subsidiary in Ukraine, and the ownership decision begins where it ends.
A smaller retained operation needs its own economic case
Exit is not always total, and divesting Ukrainian operations in stages is visible in the deal record even though no statistical series measures it. KPMG's 2025 review identified agricultural transactions in which owners sold assets closer to the front line to rebalance geographic risk, among them two businesses in the Sumy region sold by Agroprosperis, the farming group owned by funds managed by NCH Capital. The group has since agreed to sell a farming company in central Ukraine, a transaction cleared by the Antimonopoly Committee in February 2026. A foreign owner can reduce exposure through a series of smaller sales to domestic buyers while continuing to operate elsewhere, although the public record does not show where such a sequence is meant to end.
A smaller footprint works as an ownership strategy only when something identifiable is being preserved, such as access to a market that would be costly to re-enter, key customers, a critical capability, licences or an option on recovery. Whether that holds is a company-level question rather than one the national data answer. The reduced business needs viable economics of its own, a capital requirement the parent is willing to fund, a management burden proportionate to its value and enough transparency for the owner to see whether its purpose is being served. How headquarters secures that transparency is a question of keeping visibility and control over a Ukrainian subsidiary.
The currency rules shape the economics of retention as well. Profits earned since the start of 2023 can be paid out within the monthly cap and the incentive limits, while earlier retained earnings and the invested capital stay in Ukraine. A retained business therefore returns cash to its parent more slowly than its accounts suggest, and what to do with the balance is a company-level question.
Closure consumes cash and forfeits options
When no acceptable buyer emerges, winding down operations in Ukraine can look like the simplest exit. Closure carries costs that no national dataset records. It ends the possibility of selling later, including after conditions improve, and forgoes whatever a buyer would have paid for the customers, licences, team or market position. It also absorbs cash and senior management time in settling employment, contractual, tax and creditor obligations, and some liabilities can outlast the operation itself.
Liquidation in Ukraine follows a statutory process that sets minimum procedural requirements and constrains the timetable. Creditors must be given at least two months to present claims, and the tax service runs an unscheduled documentary audit before a company can be struck off. An objection from the tax or pension authorities blocks deregistration until it is resolved, as the State Tax Service describes. The detailed liquidation, employment and tax steps belong with Ukrainian legal, tax and accounting advisers, and the timetable belongs in the owner's comparison from the outset.
Liquidation does not by itself resolve whether the remaining proceeds can be transferred out of Ukraine. The NBU has not yet authorised the return of investments, and a transfer outside the permitted list requires an individual NBU permit, for which the applicant must show the transaction's importance to the state under martial law. Whether cash left once obligations are met can be moved, and on what basis, therefore has to be established for the specific company before closure is chosen. The NBU's own reasoning in 2024 cited the risk of foreign-owned companies winding down, which shows how the regulator views such closures.
A decision to close should rest on an explicit comparison of the cash each path would produce or consume. That means what a realistic sale would realise and where it would be paid, what continued ownership in some form would cost and return, and what closure would absorb and leave behind.
What the evidence establishes in September 2026
The national record is strong on the environment and silent on the enterprise. It shows a market that functions, a buyer field led by Ukrainian capital and by foreign incumbents already present, regulatory gates that set the timetable, and a payment regime that separates completing a sale from moving its proceeds. It does not price a business, identify its buyer or measure what would be left of it once separated from its parent.
Issue | National evidence | Company evidence |
Saleability | Deals complete across many sectors | Whether a buyer has a reason to own this business |
Value | Partial disclosure, no benchmark multiple | Transferable earnings and separation costs |
Buyers | Ukrainian buyers lead by deal count | Which buyer fits this asset |
Proceeds | Proceeds paid in Ukraine cannot be sent abroad | How the deal is structured and paid |
Retain or close | Dividends move within limits, capital does not | Purpose, economics and the cost of closure |
Three things bear on the coming period, and each sits at a different stage of adoption. The NBU restrictions, with their dividend and incentive-limit exceptions, are in force now, alongside a temporary government commission on screening foreign direct investment created in January 2026 as an advisory body. The NBU's three-stage strategy has been adopted and is still being implemented, and its final stage would restore repayment of loans and investments, though it carries no date and can be paused if risks intensify. A draft law on screening foreign direct investment in critical infrastructure, strategic subsoil use and military and dual-use production has been proposed but not adopted, and parliament placed it on the session agenda on 1 September 2026 while it remains in committee. Both KPMG and the Aequo study expect stronger activity in the second half of 2026, which is an expectation rather than an established trend, and nothing published supports a forecast of when capital repatriation will reopen.
For an owner, the boundary is the practical conclusion. Public and national evidence can establish the transaction environment, the pattern of buyers, the regulatory constraints and the routes available for cash. It cannot determine whether this particular business should be sold, retained in a smaller form or closed, because that turns on its economics without the parent, on the buyers that could credibly want it and on the cash each path would leave. Those facts sit inside the company, and an independent senior view for owners and boards is most useful while all three paths remain open.
If you are weighing sale, retention or closure of a Ukrainian business, speak with a senior advisor before the decision is framed as a transaction.