Between 2023 and 2025 the conditions facing companies in Ukraine changed repeatedly. Consumer inflation fell to 5.1% in 2023, rose to 12.0% in 2024 and eased to 8.0% in 2025. The National Bank's key policy rate moved from 25% down to 13% and back above 15%.
The share of large and medium-sized enterprises recording a loss barely moved. State Statistics Service data put it at 28.1% in the first quarter of 2023 and at 26.8% in the first quarters of both 2024 and 2025. Roughly a quarter of large and medium-sized Ukrainian companies lose money in better national quarters and in worse ones.
That stability is where diagnosis of an underperforming subsidiary in Ukraine has to begin. National conditions change a great deal while the proportion of companies failing inside them moves very little, which does not make the operating environment unimportant but does mean a national average describes a distribution rather than a company. A loss-making Ukrainian operation is therefore not evidence about the Ukrainian economy, and Ukrainian economic data are not evidence about the operation. The same declining margin can follow from a market the business cannot control, a model that no longer covers its cost base, execution that loses value the model should deliver, or management that is not equal to the job the business now requires. Each supports a different owner decision, and more than one can be true at once.
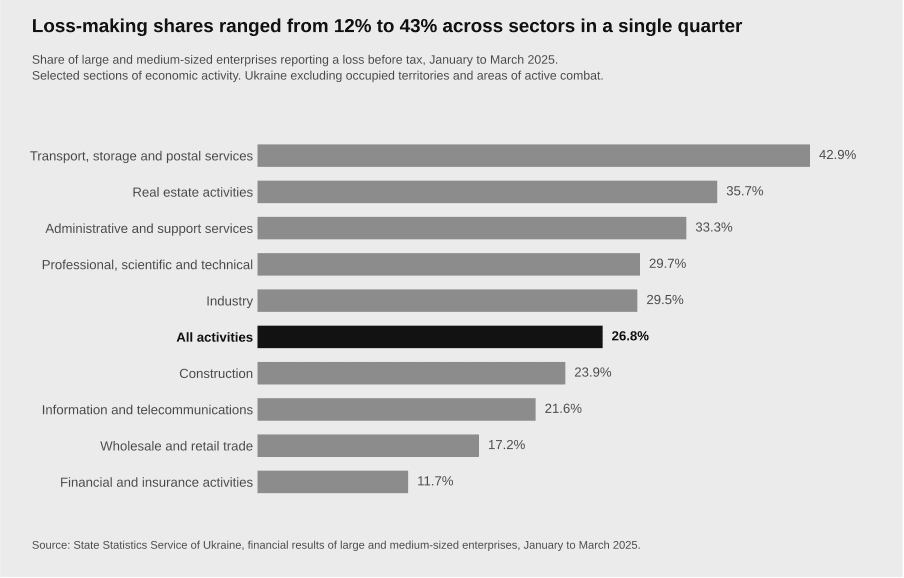
Share of large and medium-sized enterprises reporting a loss before tax by sector, January to March 2025. Data from the State Statistics Service of Ukraine.
What changed outside the company
Energy supply remains the external constraint with the broadest exposure across Ukrainian businesses. The National Bank estimated the electricity deficit at 2% of consumption across 2025, then raised its first-quarter 2026 estimate to 12% and its full-year 2026 estimate to 6%. Logistics then changed twice in quick succession, and it reached a narrower group. Rail freight tariffs rose 30% on 1 August 2026, the first indexation since 2022, with a further 15% scheduled for 1 January 2027. Traffic into the Greater Odesa ports, which handle around 90% of agricultural exports, collapsed after attacks on shipping in July, and seven vessels entered in the first eleven days of August against 169 in July.
Labour is the most persistent constraint, leading the list of war-related obstacles in the Institute for Economic Research and Policy Consulting monthly survey of mainly industrial enterprises for well over a year and cited by 66% of respondents in July 2026. Money costs more as well, since the National Bank raised the key policy rate to 16% on 17 September 2026 against 9% at the end of 2021, and the average hryvnia rate on business loans was 15.3% in the second quarter of 2026.
These figures establish that particular pressures are real for companies with particular exposures, and nothing about whether one subsidiary lost share, priced badly, over-ordered or let overhead drift. The useful comparison is narrow, because sector separates results more sharply than country does. In the first quarter of 2025 transport and storage ran at 42.9% loss-making against 17.2% in wholesale and retail trade, inside the same national figure of 26.8%. An operation deteriorating while comparable businesses hold steady has a weaker external defence than its results suggest.
Whether the model still covers its cost base
An operation can execute competently while the economics beneath it stop working, and some external changes alter the arithmetic of a business permanently.
The EU's Carbon Border Adjustment Mechanism entered its definitive phase on 1 January 2026, and its reach is concentrated rather than general, since covered goods were about 15% of Ukraine's exports to the EU in 2025 and iron and steel are 92% of those. The German Economic Team puts the 2026 charge on hot-rolled coil at roughly USD 114 per tonne, working from the European Commission's default emission values that most Ukrainian producers will be forced to use because verification cannot be completed in time. Its modelling projects a fall of USD 1,175m in those exports in 2026, which is a scenario rather than a result, though the charge is already law and rises as EU free allowances are withdrawn. Timing matters for anyone reading a 2026 income statement, because certificates cannot be bought before February 2027 and are not surrendered until September 2027, so a steel exporter whose margin fell this year has not yet paid it.
What separates a structural change from a temporary downturn is a documented shift in rules or cost structure that has persisted, not the number of months weak trading has lasted. Rail indexation qualifies on that basis, while the port closure does not yet, because it turns on security and insurance rather than on a rule. Where a structural change is established, the owner has to ask whether the existing model, cost base and capacity still produce an acceptable return at volumes the operation can realistically reach. A model built around cheap rail, cheap power, abundant labour or an export route that no longer functions will not be rescued by better discipline inside it. That decision belongs with business transformation and restructuring, and the owner takes it before any programme is designed.
A higher cost base is not proof of inefficiency
Cost ratios worsen in a contraction partly for mechanical reasons. Across 7,629 companies over twenty years, Anderson, Banker and Janakiraman found that selling, general and administrative costs rise 0.55% for each 1% of sales growth but fall only 0.35% for each 1% of decline. A cost base that has not tracked volume down is a normal finding rather than a verdict.
Some of that increase purchases continuity rather than reflecting waste. Battery imports reached USD 1.5 billion in 2025, and four in five European Business Association members report disruption from outages. Measuring that spending against a pre-war cost structure will misprice it.
Payroll is where the judgement is hardest, because in Ukraine pay is now partly a regulatory threshold rather than a market choice. Reservation of liable employees runs through the critically important enterprise regime in Cabinet Procedure No. 76, amended by Resolution No. 692 of 30 May 2026, which caps reservation at 50% of liable staff for most companies and, from 1 September 2026, requires an average wage of at least three minimum wages, or UAH 25,941. A subsidiary that trims payroll below that threshold can lose the status, lose the reservation with it and lose people to mobilisation within weeks, which is a cost saving that destroys capacity. Resilience is not a blanket justification either, and the test for any single cost is what would stop happening if it were removed, and whether that consequence is worth more than the cost.
Where viable economics are lost
Profit margins among large Ukrainian companies leave little room to absorb commercial or operating inefficiencies. Among large Ukrainian companies profitable in 2025, half earned a return on sales below 2.6%, according to registry data compiled by Opendatabot. At that level a few points of unmanaged discount or an extra month of stock can move a business from one group to the other.
In a foreign-owned subsidiary the reported margin is partly an accounting outcome of intragroup pricing, and it has to be tested before anything is concluded from it. Ukraine's transfer pricing rules in Article 39 of the Tax Code apply once annual income passes UAH 150 million and transactions with one counterparty pass UAH 10 million. Management fees, royalties, interest and the price at which goods move between parent and subsidiary can absorb most of a thin margin, and the Cabinet approved a draft law widening the scope of controlled transactions on 20 August 2026. A subsidiary reporting 2% after paying the group may be a sound business inside a badly designed structure, and no amount of operational work will fix that.
Where revenue does not convert into margin, the usual explanations are pricing and discount control, customer and channel mix, or a cost-to-serve that has moved without being repriced. Where margin does not convert into cash, they are inventory, receivables and procurement terms, part of which is the external price of longer routes and safety stock, though at a financing cost above 15% each additional month carries a measurable charge. Both are worsened by slow decisions, unclear accountability between commercial and operational functions, and management capacity too thin to close problems out.
What the company's own record can be made to show
Ukraine adds a cash-flow mechanism unconnected to commercial performance that is often missed from abroad. Registration of a VAT invoice can be suspended under the monitoring procedure in Cabinet Resolution No. 1165, amended with effect from 27 September 2025, and a supplier carrying risky taxpayer status can find invoices blocked, customers withholding payment and receivables ageing for reasons unconnected to trading. Tax debt, enforcement proceedings, pledges and open litigation sit in public registers, and an afternoon spent in them often explains more about a cash problem than a week of interviews.
The comparison that matters is more available than owners assume. Roughly 429,800 companies filed financial statements for 2025, and under the Law on Accounting and Financial Reporting large and medium-sized enterprises, natural monopolies and public interest entities must publish audited annual accounts, which are not treated as a commercial secret. Named local competitors can be benchmarked on revenue, margin and working capital rather than on impressions.
Some questions cannot be answered from Ukrainian sources at all, and substituting a proxy for them is the commonest error in these reviews. Market share in most business-to-business segments is not measured, so a share claim has to be rebuilt from customer-level data or dropped. Statistical reporting has been voluntary under martial law and excludes occupied territories and areas of active combat, so national series describe only the companies that report. Reporting weakness inside the business belongs here as evidence rather than as a separate subject, because where variances arrive late or cannot be reconciled the owner cannot yet attribute anything to anyone, and the first problem to fix is visibility rather than performance. Where the model is sound and value is being lost inside it, the intervention is operational and belongs with operations consulting and execution support.
Testing management against the mandate it now has
No national evidence establishes how well foreign-owned Ukrainian subsidiaries are managed, how often owners replace local leadership, or how frequently management causes underperformance. No credible aggregate measure exists, and a proxy would manufacture a finding rather than establish one. Management performance can only be assessed from the company's own record.
Management performance can be misdiagnosed in either direction. Research on how companies explain their results finds a persistent pattern of attributing poor outcomes to external conditions and good outcomes to management action, and Ukraine offers an unusually large supply of the former. The reverse assumption, that weak results prove weak local management, is no better supported, and it surfaces most often when the owner is distant and the reporting is thin. Replacement changes the team without establishing that the team was the cause, and it will not produce recovery where the cause lies elsewhere.
Useful evidence is specific to the mandate the operation now carries. It includes forecast accuracy across several cycles, the quality of variance explanation, commercial results measured against comparable businesses rather than budget, whether agreed actions were executed, and whether known problems were resolved or repeated. Some items belong on that list in Ukraine and almost nowhere else, such as whether critically important status was applied for and held, whether blocked invoices were cleared quickly, and whether the transfer pricing file would survive an inspection. Competence is mandate-specific too, and leading a growing operation, protecting cash through a contraction, rebuilding a commercial model and preparing a business for sale draw on different capabilities, so the manager who was right for one may not be right for the next. Owners who need that judgement formed independently of the reporting line can take it to owner, board and investor advisory.
What the diagnosis supports
Not every underperforming business needs redesign, and one whose competitive position has genuinely gone will not recover by executing harder. Six destinations follow a completed diagnosis, and the owner can improve execution inside the current model, redesign the model, strengthen or change leadership, continue under closer oversight while evidence accumulates, sell, or exit in an orderly way where the economics no longer justify continued operation.
One Ukrainian feature changes the arithmetic of holding against selling. A profitable subsidiary is not automatically a source of cash to its owner, because dividend repatriation runs under National Bank Resolution No. 18 and, after the August 2025 amendments, covers dividends accrued from 1 January 2023 within a monthly cap of EUR 1 million. Larger amounts move only against an investment limit created by new foreign equity or a loan limit created by new foreign borrowing, which the package effective 11 August 2026 allows related companies to share. Earnings accrued before 2023 remain trapped, and an owner weighing whether to keep the business should price that alongside the operating result.
Interim leadership sits inside the third of those destinations, and only where a leadership or transition problem has been established. It is a time-bound bridge with a defined mandate, used to restore decision capacity, carry a transition or stabilise management while a permanent answer is prepared. The case for it is strongest where a permanent appointment would be premature, because the future model is unresolved or the business may be sold within the year. An interim arrives without standing and has to build it quickly, which is why the mandate and end point need defining before anyone arrives. It is not executive search, not restructuring delivery and not a default response to weak results, and reinforcing the existing team or tightening owner oversight is often the proportionate answer.
One boundary holds throughout the diagnosis, because a business that needs cash, supply, delivery, security or authority stabilised within days rather than quarters is no longer in chronic underperformance and belongs to crisis management. Everything above assumes there is still time to establish the cause, and in Ukraine most of the material needed to establish it is already filed, registered or sitting in the subsidiary's own reporting. An owner who intervenes before collecting it usually buys a remedy for the wrong problem, and finds out a year later with less cash and fewer options.
UA Consulting works with owners, boards and investors on independent assessment of Ukrainian operations before the decision is taken. Get in touch.