Buying a company in Ukraine is a live route for foreign capital, and the transaction record has recovered steadily since 2022. The most recent annual review of Ukrainian M&A counts 63 deals for 2025, the highest number since 2021, with a further 40 recorded in the first half of 2026. Price evidence has not kept pace with that recovery, because only 57% of the 2025 transactions disclosed a value.
Who is buying matters as much as how many deals close. Ukrainian buyers took most of the transactions involving Ukrainian targets in both half-years covered by that data, while inbound deals by foreign buyers doubled from a low base. Aequo attributes much of the domestic strength to currency controls, which have left large local groups holding hryvnia that cannot easily be moved abroad. Disclosed value swings far more violently than deal count, so the two measures should be read separately.
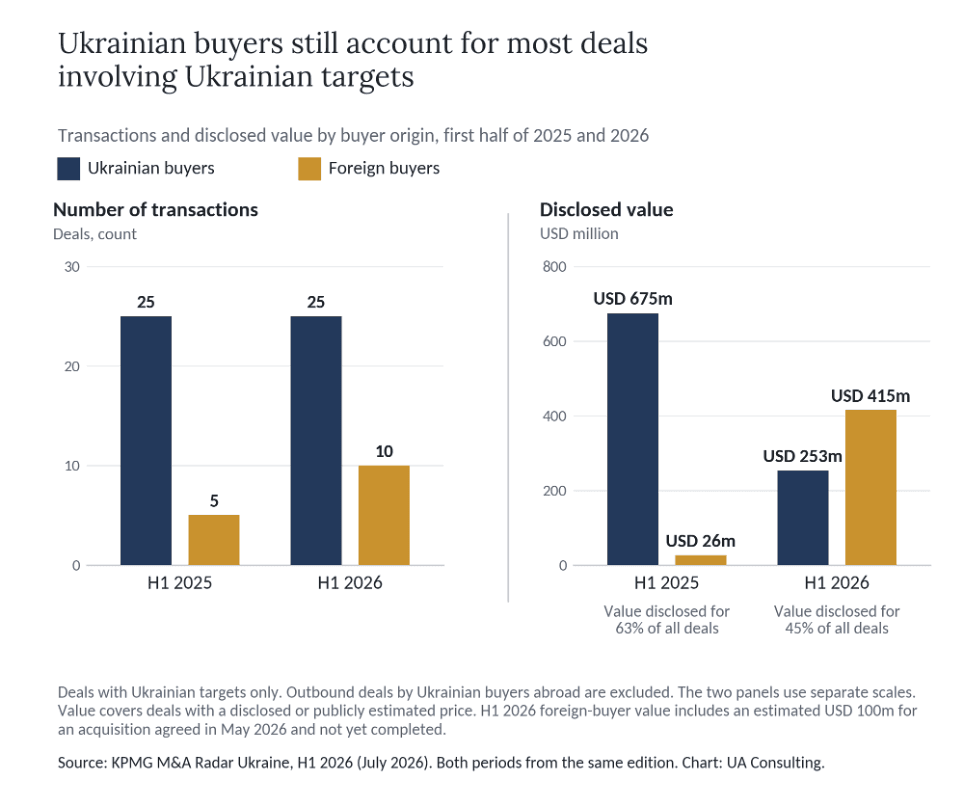
The national figures need careful handling before they inform a decision on acquiring a Ukrainian company. KPMG counts deals above USD 5 million together with undisclosed deals whose targets turn over more than USD 10 million, and it fills prices from company announcements, data providers and published estimates. By its own account, no value was published for 54% of the Ukrainian deals it has recorded since 2013. The database is also revised as lapsed deals fall out and prices surface later. KPMG first reported the first half of 2025 as 34 deals worth USD 716 million and, a year later, as 35 deals worth USD 1,029 million.
Table 1. Ukrainian M&A as published, and what each figure can support
Period | Transactions | Disclosed value | What the figure shows |
2021 | 75 | Almost USD 2 billion | Pre-invasion reference. More than 20 deals announced in 2021 were later cancelled |
2022 | 28 | USD 494 million | Lowest count since the series began in 2013 |
2023 | 47, later restated as 49 | About USD 1.2 billion | One USD 500 million telecoms deal supplied close to 40% of annual value |
2024 | 49, later restated as 50 | About USD 1.1 billion | 64% or 65% of deals disclosed a value, depending on the edition |
2025 | 63 | About USD 1.2 billion | 57% disclosed a value and three deals supplied about half the total |
First half of 2025 | 34, restated as 35 | USD 716 million, restated as USD 1,029 million | The same six months reported a year later, once more prices surfaced |
First half of 2026 | 40 | USD 978 million | Interim reading, with 45% of deals disclosing a value |
2025 on the Aequo and Forbes Ukraine definition | 41 | About USD 1.7 billion | Different inclusion rules, including a minimum stake of 10% |
Sources: KPMG M&A Radar 2023, 2024, 2025, H1 2025 and H1 2026, with the 2021 value as reported by the Kyiv Independent. The final row is from the Aequo and Forbes Ukraine study.
Definitions move the market's apparent size as much as disclosure does. The Aequo and Forbes Ukraine study counts 41 transactions for 2025 against KPMG's 63, mainly because it requires the buyer to take at least 10% of the asset. Value is concentrated in both datasets, with about half of the 2025 total sitting in three deals on KPMG's count and 51% in five deals on Aequo's. National statistics can confirm that acquisition is a working route and that scarce operating positions are changing hands, but they cannot price a target, and neither dataset measures a war discount or the share of sellers acting under distress.
Buy or build turns on the capability being acquired
Acquisition carries costs that organic entry avoids, because the price capitalises the seller's view of the future, the buyer inherits the target's history and the approval timetable sits outside its control. Those costs earn their place only where the capability being bought would take materially longer, cost more or carry greater execution risk to build. Wartime conditions lengthen the organic route, and KPMG's mid-2026 review points to tight labour markets, skills gaps and energy supply risks that an operating business has already absorbed. For manufacturers, the prior question of whether to produce in Ukraine at all is covered in our analysis of manufacturing in Ukraine.
Current earnings are a weak guide to what is actually being bought. Bunge completed its staged acquisition of the ViOil crushing plant in the fourth quarter of 2025, although the plant's operating company had reported a net loss for 2024. That points to installed capacity rather than recent trading as the basis of the price. Table 2 sets out four capabilities acquired in different sectors, why each is slow to reproduce and what the buyer still has to establish.
Table 2. What an acquisition can secure that organic entry would have to reproduce
Capability acquired | Why it is slow to build | Ukrainian evidence | What the buyer still has to establish |
Processing capacity | A site, construction, grid connection and a supply base all have to be secured before output begins | Bunge moved from a 15% stake and an option to full ownership of the ViOil plant, completing in the fourth quarter of 2025 | Whether utilisation and margins recover inside the buyer's own sourcing and export system |
Regulated market position | A licence, capital and nationwide distribution take years to assemble, and share has to be won from incumbents | PZU agreed in May 2026 to buy MetLife Ukraine, which wrote 49.2% of life premiums in 2025 | Whether customers, bank and broker partners and staff stay through a long approval period |
Two-sided digital platform | Pharmacies and consumers have to adopt the platform together before either finds it useful | Kyivstar bought Tabletki.ua, used by about 12,000 pharmacy outlets in 2024, close to 70% of pharmacy retail | Which uses of customer data remain available under the conditions attached to clearance |
Port infrastructure | Berth length, depth and a position inside a working port cannot be created on the buyer's timetable | DP World sold its 51% of the TIS container terminal in March 2026 as part of a portfolio decision | Which operating rights, customer contracts and shareholder arrangements stay with the terminal |
Where credible acquisition targets actually come from
Listings of businesses for sale in Ukraine describe a narrow and unrepresentative part of the market. The visible formal channel is privatisation, which now includes assets confiscated from sanctioned owners, and in KPMG's 2025 data every privatisation went to a domestic buyer. Auction conditions decide whether anyone transacts at all, and the Odesa Portside Plant drew no registered bidders in November 2025. Its sale has been rescheduled for 19 October 2026, with a starting price above UAH 4.3 billion and an investment obligation of at least UAH 500 million.
The transactions foreign buyers have actually completed came from owners' circumstances rather than from any organised market. DP World and MetLife each sold a Ukrainian business as part of a wider portfolio decision, and the farming group Agro-Region changed hands once its owner treated a long-held investment as ready to sell. MHP's head of M&A expects the retirement of owners who built businesses in the 1990s to release further assets. Because most of this supply is never advertised, the acquisition profile has to precede the target list, fixing the capability sought, the scale and location that make it useful and the ownership situations the buyer can work with. The same decision from the owner's side is examined in our analysis of selling a business in Ukraine.
Distressed assets in Ukraine deserve particular care, because no national dataset classifies transactions as distressed. KPMG records agricultural owners selling assets near the front line to rebalance geographic risk, Horizon Capital says it is preparing exits without forced sales, and Aequo reports owners of sound businesses refusing an automatic war discount. That evidence neither proves nor excludes distressed opportunities, so any such claim has to be tested company by company.
Scarcity does not establish transferability
Market evidence can show that a capability is scarce, but not whether the performance attached to it survives a change of ownership. That depends on the management team, customer and supplier relationships, licences, change of control terms, financing, support from a former parent and, increasingly, on what a regulator allows. When the Antimonopoly Committee cleared Kyivstar's purchase of Tabletki.ua, it attached eight conditions on competition and the use of customer data, limiting how far the platform can be combined with the group's existing health services. Detailed testing of customers, revenue durability, margins and capacity belongs to commercial due diligence, while the acquisition decision needs the earlier judgement about which dependencies could break the investment case.
The choice between buying shares and buying assets follows from the same analysis. A share deal keeps the operating company intact, with its contracts, staff, permits and history, including liabilities the buyer would rather not inherit. An asset deal can leave some of that exposure behind at the cost of the relationships and permissions that made the assets productive. Each principal transaction discussed here was a purchase of shares or corporate rights, which suits capabilities that sit in a licence, a policy book, a user base or a network of contracts. Carving a business out adds its own timetable, and MHP's purchase of a meat processing business required the seller's company to be split in two beforehand, which took nine months. Whichever route is chosen, the legal and tax consequences need Ukrainian specialist advice.
Valuation, structure and the currency constraint
No defensible market-wide multiple exists for Ukraine acquisitions, and the rare disclosed case shows why estimates are unreliable. Market estimates cited by KPMG had put Tabletki.ua at USD 30 million to USD 80 million, whereas Kyivstar disclosed consideration of USD 160 million, equal to 8.0 times the platform's unaudited trailing profit. That multiple belongs to one platform and one buyer's synergies rather than to the market. Buyer and seller views also diverge over future cash flows, country risk, transferability and synergies open to a single bidder, and Ukrainian currency rules widen the gap. The National Bank still caps dividend repatriation at the equivalent of EUR 1 million a month. The exceptions it has added, most recently in August 2026, are tied to new foreign equity and, since January 2026, to new foreign borrowing.
Those constraints show up directly in negotiations, where FinPoint has found owners of successful companies reluctant to sell for hryvnia and Kernel and IMC ended talks over price and other terms even after obtaining antitrust clearance. Where the gap reflects uncertainty rather than disagreement, structure can carry part of it. Bunge moved from a minority stake with an option to full control, and USD 86 million of its USD 134 million preliminary consideration was contingent or deferred rather than paid at completion. PZU took a different route and moved war and political risk outside the price by insuring its investment with KUKE, the Polish export credit agency. KPMG observed deferred components of up to a quarter of consideration in 2023, and Aequo lists escrow, seller financing and phased transfers among the mechanisms in use, although no dataset measures how common they have become.
Approvals set the timetable and can reshape the deal
Regulatory clearance is where the buyer's timetable meets the state's competition and security priorities. Aequo notes that the Antimonopoly Committee now examines ultimate beneficial owners, the origin of capital, sanctions exposure and the strategic importance of the asset alongside market shares. A standard review runs up to 45 days once an application is accepted, while complex cases can pass three months. Kyivstar needed three filings and more than a year to reach clearance for Tabletki.ua, and PZU's purchase requires both central bank and competition approval before an expected completion in 2027. Thresholds and filing procedure are covered in our analysis of antitrust and merger control in Ukraine.
Foreign investment screening is still a prospect rather than a gate. Draft Law No. 14062, registered in September 2025 and accompanied by an alternative text, remained in committee in September 2026 and would introduce prior review of foreign investment in critical infrastructure, natural resources and military and dual-use production. The Institute of Legislative Ideas supports the principle as a matter of economic security while criticising the 150-day review period in the registered draft, so the final design is not settled. A Cabinet of Ministers resolution has meanwhile created an interdepartmental screening commission, in force since February 2026, although Ukrainian legal commentary notes that no mandatory procedure yet applies. A buyer in a sensitive sector should therefore expect scrutiny of ownership and capital origin now, and treat a formal regime as possible rather than certain.
What a buyer settles before signing
The order of work decides how much the buyer knows when it commits. Strategic fit and the acquisition profile come first, followed by early red flags on ownership, sanctions and title, then commercial and operational testing, specialist legal, financial and tax diligence, and finally valuation, risk allocation and completion readiness. Sellers screen buyers in parallel, and Aequo reports that capital origin, ownership structure and sanctions exposure are examined before full negotiations begin. Early approaches therefore need the information discipline set out in our analysis of confidential advisory in Ukraine.
National evidence takes a buyer only as far as the environment. Management dependence, capacity utilisation, the quality of reported earnings and the durability of customer relationships are settled at target level, together with the control and reporting arrangements examined in our analysis of controlling a Ukrainian subsidiary. UA Consulting supports buyers through that sequence, from acquisition logic and target assessment to completion, as part of its M&A advisory and transaction support.