The reason for producing locally sets the economics
Three distinct rationales lead foreign companies towards production in Ukraine, and each rests on different economics. The first is serving Ukrainian demand, where the company already sells here or expects to, and local capacity shortens delivery times, reduces landed cost and improves service. This case depends on accessible demand rather than on market size, and accessible demand is narrower than national figures suggest once regional access, customer creditworthiness and established local competition are taken into account. Several of the recent foreign plants make construction products, whose volumes depend on how much reconstruction need turns into funded and executable projects. How that conversion reaches a supplier is examined in our analysis of the construction materials market in Ukraine.
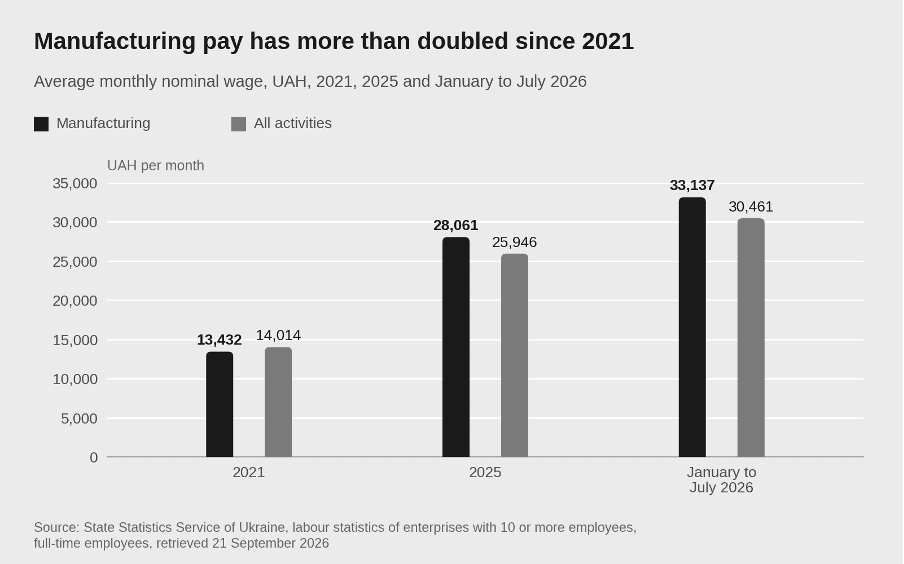
Source: State Statistics Service of Ukraine, average monthly nominal wage of full-time employees in enterprises with 10 or more employees.
The second case is production localisation undertaken to secure market or procurement access. Manufacturing locally can change how certain buyers assess eligibility and supply security, or remove the lead times that lose contracts. The case therefore rests on access gained, and on identifying the specific customers or procurement processes that treat local production differently.
Ukrainian policy gives local production a distinct advantage in two areas where localisation can directly affect access to demand. Public buyers of listed industrial goods must apply a minimum localisation level that rises each year until 2028. Under the new public procurement law, the rule covers purchases of UAH 1 m or more from 24 August 2026, including goods supplied within works and services.
The rule does not apply to goods originating in countries that are party to the World Trade Organization's Government Procurement Agreement or to other relevant treaties with Ukraine, a group that includes the European Union (EU). Under the earlier rules that exemption applied only above the treaty value thresholds, about UAH 4.9 m in 2022 and 2023, so smaller public contracts required localised goods whatever their origin. The sources reviewed do not settle how the new law treats that band, which is where local production could give a European manufacturer procurement access that exporting from the EU does not.
The second mechanism changes the buyer’s effective price for locally manufactured equipment. State programmes reimburse 25% of the cost of qualifying Ukrainian-made agricultural machinery and 15% for construction, municipal, specialised and energy equipment, provided local content reaches the required threshold. For a producer of such equipment, local manufacture changes the price its customer compares with an import. Unlike the procurement rule, this advantage applies to purchases by private enterprises.
The third rationale is to use Ukraine as a production base for exports, principally to the EU. The relevant comparator is then the company's existing or alternative European sites rather than the Ukrainian market, and the economics turn on landed cost into the destination market. The wood-panel line launched in November 2024 illustrates the model, with 60% of its output intended for export to the EU and the United States.
A project may rely on more than one rationale, but its investment case still needs one primary economic driver. The investment case becomes difficult to defend when several are combined without establishing which one actually carries the economics, because a proposal claiming domestic demand, procurement access and export advantage at once often cannot demonstrate sufficient volume from any single source. Reviewers are then left with no primary assumption to test.
What production capability is actually available today
A foreign manufacturer needs to know what capability it can draw on now, which is a narrower question than how Ukrainian industry has performed in aggregate. The aggregate nevertheless frames the answer for any specific process. Industrial output fell by more than a third in 2022 and, on our calculation, recovered to about 70% of its 2021 level by 2024, where it held in 2025. In the first half of 2026 it was 0.2% below the same period of 2025, a result driven by lower energy output while mining and manufacturing grew.
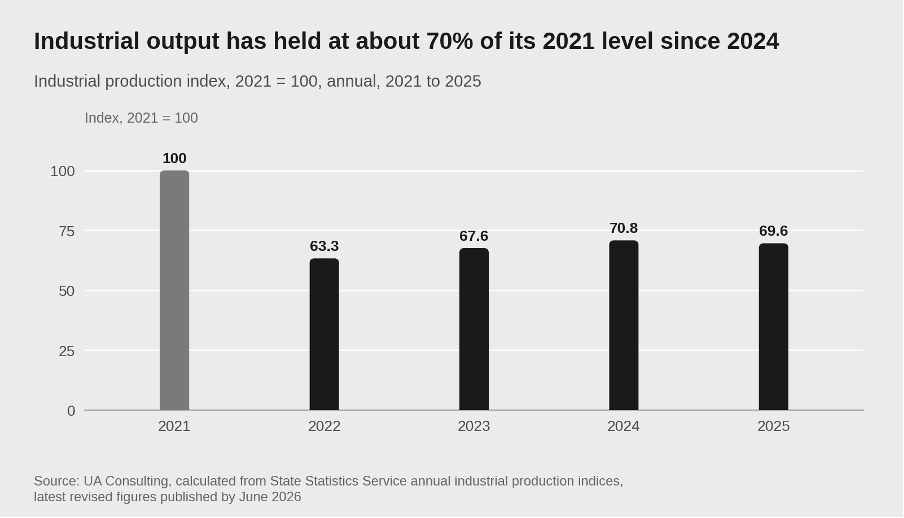
Source: UA Consulting, calculated from annual industrial production indices of the State Statistics Service as reported on 26 March 2025 and 4 June 2026.
Part of the industrial capital stock has been lost since 2022, and part has been rebuilt. The fifth joint damage and needs assessment records direct damage to commerce and industry of USD 19.2 bn up to the end of 2025 and notes that one in four large firms experienced damage during 2025. It puts recovery needs in the sector at USD 63.3 bn for 2026 to 2035. Capacity has also moved westward under the state relocation programme of 2022 and 2023, while the capability to staff and maintain it has not kept pace.
Four practical questions determine whether a production process is operationally viable in Ukraine. The first is whether the required equipment can be installed and commissioned by contractors already present in the country, since importing an installation team lengthens the schedule and raises cost. The second is whether local engineering and maintenance capability exists for the specific process, because otherwise every technical intervention requires travel. The third concerns the depth of the supplier base for inputs the company assumed it could buy locally, and the fourth, often the binding constraint, is whether management of the required calibre can be recruited.
Recent foreign manufacturing investments provide some evidence of where Ukraine’s industrial capabilities are already sufficiently developed to support new production. The foreign plants reviewed for this analysis are concentrated in wood-based panels, food and beverages, personal care and construction products. They include a Finnish maker of precast connections that opened a plant in April 2025 and a Danish brewer that added a canning line worth more than EUR 12 m in May 2026. These sectors draw on an established domestic raw-material and supplier base, although that reading is an inference from where capital has gone rather than a measured assessment of capability.
Commissioning timelines in Ukraine can extend beyond the original project schedule, particularly where production depends on imported equipment and technical support. A British consumer-goods group began building a EUR 20 m personal-care plant in March 2024 with completion planned for the end of that year, and the host industrial park still listed it as under construction in July 2025. No opening date was found in the sources reviewed. Processes that rely on imported machinery and spares add those import lead times to every commissioning step and repair, which affects both the schedule and the ongoing cost of keeping a line available.
Manufacturing costs in Ukraine depend on more than the wage bill
Wage comparison dominates most cost analysis of production in Ukraine and is the least reliable part of it. Several items that European cost models either omit or underweight carry real weight in a Ukrainian operation, and energy is the clearest of them because it affects both reliability and price. Where a process cannot tolerate interruption, backup generation or a degree of autonomy becomes a permanent cost line with its own capital, fuel and maintenance requirements, and a model that leaves it out understates unit cost from the first day. Grid power has also become dearer, as the base-load price on the day-ahead market averaged UAH 5,292 per megawatt-hour in 2025, 17% more than in 2024, and the monthly average reached UAH 9,786 in February 2026.
Inbound material dependency matters wherever inputs are imported, because freight, customs handling and buffer inventory tie up working capital that a site inside the EU would not require. Insurance is priced differently, and utilisation assumptions have to rest on the availability of power and people, since nameplate capacity overstates output. Management overhead is also higher for any operation a group cannot visit easily, and that cost is real even when it appears in no project budget.
Gross wage differentials do not translate directly into differences in total employer labour costs. Eurostat puts non-wage costs at 4.8% of total labour costs in Romania and 18% in Poland in 2025, against an EU average of 24.8%. Gross wage differentials therefore translate unevenly into employer cost, and the same gross salary can mean a different bill in each country.
In Ukraine the employer adds a unified social contribution of 22% to gross pay, which on our calculation equals about 18% of total employer cost when only that statutory contribution is counted. The structure of employer cost is therefore close to Poland's, and the gap lies in pay levels and output per worker. What belongs in the model is cost per unit produced, since cost per hour worked ignores productivity. The model then has to establish whether risk-adjusted total economics outperform the realistic alternative for this specific operating model, which may be continued import, contract production or acquisition of existing capacity.
Average monthly pay in Ukrainian manufacturing more than doubled in hryvnia terms between 2021 and 2025 and has exceeded the economy-wide average since 2024, according to the State Statistics Service. Labour shortage is now the obstacle industrial enterprises cite most often, named by 69% of respondents in the August 2026 business survey of the Institute for Economic Research and Policy Consulting (IER). Foreign manufacturers have nonetheless committed capital here, including an Austrian wood-panel producer, a Swiss food group and a German building-materials manufacturer that opened lines or plants between November 2024 and August 2025.
Manufacturing in Ukraine can be commercially defensible, but only where a company can identify one specific economic reason for producing locally and that reason survives a realistic test of total cost, workforce availability, energy reliability, operating capability and resilience. Lower wages on their own do not constitute an investment case. Neither does the scale of reconstruction needs, put at almost USD 588 bn for 2026 to 2035 in the latest joint damage and needs assessment. Such an aggregate says nothing about accessible demand for a particular product.
This analysis addresses the decision that precedes location, project design and contracting, namely whether local production belongs in a company's footprint at all. The wider operating context is set out in our guide to doing business in Ukraine. Wages are nominal and in hryvnias as published by the State Statistics Service, output is measured by the official production index, and euro conversions use Eurostat's annual average exchange rates.
Labour is a capacity constraint before it is a cost advantage
Labour availability has become the most widely reported constraint on Ukrainian industry, although its severity varies by occupation, region and production model. In the IER's monthly survey of industrial enterprises, the share naming labour shortage as a main obstacle rose from 46% in December 2023 to 61% in December 2024 and reached 71% in June 2026. It has ranked first among obstacles since late 2024, ahead of rising input prices and concerns about working safely.
Exposure differs by production process and by the size of the enterprise. In July 2026, 73% of surveyed enterprises reported a shortage of workers, with the highest shares in chemicals, building materials, metallurgy and metalworking, and food, and the lowest in woodworking and printing. Shortages were reported by 88% of large enterprises against 34% of micro-enterprises, which matters for any plant that needs a full shift pattern from the start.

Source: Institute for Economic Research and Policy Consulting, monthly survey of 472 industrial enterprises in 21 regions, July 2026.
Respondents attribute the shortage mainly to mobilisation, which 79.4% cite as a strong factor, followed by restrictions on the reservation of employees at 57.8% and departures abroad at 52.3%, according to the same July survey. Two of those causes stem from the mobilisation framework itself. Reservation is the instrument that allows an employer to retain staff liable for military service, so its limits bear directly on how a plant is staffed.
Under Cabinet of Ministers Resolution No. 76 of 27 January 2023, enterprises recognised as critically important can reserve up to half of such employees, and all of them in specified cases, according to an analysis by Poland's Centre for Eastern Studies. The Minister of Economy put the number of reserved workers at about 1.3 m in January 2026, up from about 1 m a year earlier. Reservation eases the constraint for qualifying employers without removing it, since at most enterprises it covers only part of the liable workforce.
Wage growth has been substantial in hryvnia terms, but much more moderate when measured in euros. The economy-wide average rose by 85% in hryvnias between 2021 and 2025, and in the second quarter of 2026 it was 23% above the same quarter a year earlier. Converted at Eurostat's annual average exchange rates, the rise from 2021 to 2025 was 27%, because the hryvnia lost nearly a third of its value against the euro over those years.
The distinction matters for the rationale behind a plant. An exporter earning in euros has seen its local labour cost rise far less than the hryvnia series suggests. A producer selling into Ukraine faces real wage growth that the National Bank of Ukraine (NBU) forecasts at more than 12% in 2026, before it slows to between 4% and 6% a year in 2027 and 2028.
The same forecast assumes a net outflow of about 0.2 m people in 2026, followed by net returns of about 0.1 m in 2027 and 0.5 m in 2028. The central bank ties the expected easing of wage growth to that return, which makes the labour outlook for 2027 and 2028 conditional on migration. For a plant commissioned in 2027, any such relief would arrive during its first years of operation.
Availability also varies by occupation and location, and skilled trades are the tightest part of the market. In August 2026, 58.1% of enterprises said qualified workers had become harder to find, against 36.4% for unqualified staff. Where industry has relocated, premises can be ready before a local pool of workers with the relevant competences exists. Whether a plant in Ukraine can be staffed is therefore settled trade by trade, and a staffing plan built on European recruitment speed and cost does not fit these conditions.
Energy resilience can change the production economics
Restrictions on electricity supply remain part of the operating environment, and industrial consumers are included in them. On 18 March 2026 the transmission system operator Ukrenergo applied power restriction schedules to business and industry in all regions. On 3 April industrial consumers were restricted for 16 hours, while hourly outage schedules for all consumers lasted four hours. The April episode shows that restrictions on industry can last considerably longer than those on households.
The summer of 2026 stayed well short of the worst case modelled in advance. An energy think tank's summer outlookpublished in June put the probability of consumer restrictions at up to 5% in its baseline case and allowed for up to four simultaneous queues of rolling outages in its worst case. In the event, nationwide schedules applied on the evenings of 30 June and 1 July at up to one queue during a heatwave. On 21 September the Ministry of Energy forecast no restrictions for the day.
The coming heating season is the relevant test for a production plan, and no official forecast of the winter power deficit was found in the sources reviewed. The Energy Community Secretariat described the winter of 2026 to 2027 in September 2026 as a defining test for Ukraine's energy system. What matters commercially is the cost of interruption to a particular process.
Continuous processes, temperature-controlled production and anything with a long restart cycle carry a resilience requirement that batch assembly does not. Where that requirement is high, the cost of autonomy enters the case before a site is chosen, because it can move unit economics far enough to change the decision. Our analysis of energy security and resilience for business in Ukraine examines that cost structure in more detail.
Ukraine against realistic alternative production locations
Comparison with Poland, Romania or Türkiye is often run on labour cost alone, which produces a misleading answer in both directions. Ukraine is not automatically cheaper once resilience, inventory and management overhead are priced, and it is not automatically weaker once wage levels, asset costs and proximity to particular customers are weighed. The appropriate comparator depends on the economic reason for considering Ukrainian production in the first place.
The wage gap remains substantial on the directly comparable measures available. On Eurostat's comparison of statutory minimum wages, Ukraine stood at EUR 173 a month in the first half of 2026, about a quarter of the level in Türkiye and about 15% of that in Poland, with Romania between the two. What production in Ukraine actually costs compared with Poland depends as much on output per worker, the cost of resilience and the working capital tied up in a longer supply chain as on that gap.
For a company pursuing the export rationale, the comparison is between production sites, and it holds product specification, volume and destination market constant. On that basis the dimensions worth comparing are total labour economics and productivity, energy exposure and the cost of resilience, and the depth of the inbound supply base. Outbound logistics, working capital, capital expenditure and the availability of suitable assets, management complexity, market access and the time required to reach stable output belong in the same comparison.
For a company serving Ukrainian demand, the choice between manufacturing in Ukraine and continuing to import remains open. Producing in Poland or Romania and importing into Ukraine is a real route, and the comparison runs between local production and imported supply on landed cost, lead time, service level, working capital in transit and inventory, and exposure to border disruption. Local production wins that comparison where lead time or service materially affects contract value, and loses it where volumes are too low to carry fixed cost.
Market access sits behind both comparisons, and the framework governing it was upgraded in 2025. The upgraded EU–Ukraine Deep and Comprehensive Free Trade Area (DCFTA) entered into force on 29 October 2025. The European Commission describes it as a longer-term, stable legal framework with additional reciprocal liberalisation, a new safeguard clause and alignment of Ukrainian and EU production standards.
For industrial goods the change is smaller than that description suggests, because the original agreement removed 94.7% of EU tariff lines on entry into force and phased out the remaining industrial duties by 2023. The standards alignment on which larger agricultural quotas depend covers areas such as animal welfare, pesticides and veterinary medicines. For most manufacturers the significant change is therefore the greater stability of the framework, tempered by a safeguard mechanism that either side may invoke.
Build, acquire or subcontract
Concluding that production in Ukraine makes sense does not determine how capacity is obtained, and the three routes differ in the capital committed, the control retained and the ease of reversing the decision. Setting up a factory in Ukraine as owned production suits processes that existing operators cannot run and volumes large enough to carry fixed cost. It offers full control over specification, quality and schedule, while its main uncertainties are the commissioning timeline, staffing at the required skill level and the cost of resilience. How those uncertainties play out at a particular site and under a particular investment regime is the subject of our analysis of industrial site selection in Ukraine.
Acquisition deserves consideration where a suitable operating asset exists and its capabilities are transferable. It may provide faster access to capacity, a workforce, customer relationships or operating infrastructure. The open questions are whether the asset fits the buyer's model and what liabilities transfer with it, which our analysis of buying a company in Ukraine examines.
Contract manufacturing fits where volume remains uncertain or the production thesis has not yet been tested, because the commercial case can then be proven without committing capital. The trade-off is reduced control over quality and schedule, and an arrangement whose durability has to be managed. Our analysis of contract manufacturing in Ukraine sets out where that model is credible.
What is already scheduled and what remains a target
Several conditions that shape the case already have legal force and fixed dates, while others are forecasts or policy targets. A legal schedule can be priced into a capital decision, whereas a target can only be tested against later evidence. The table below sets out their status as of 21 September 2026.
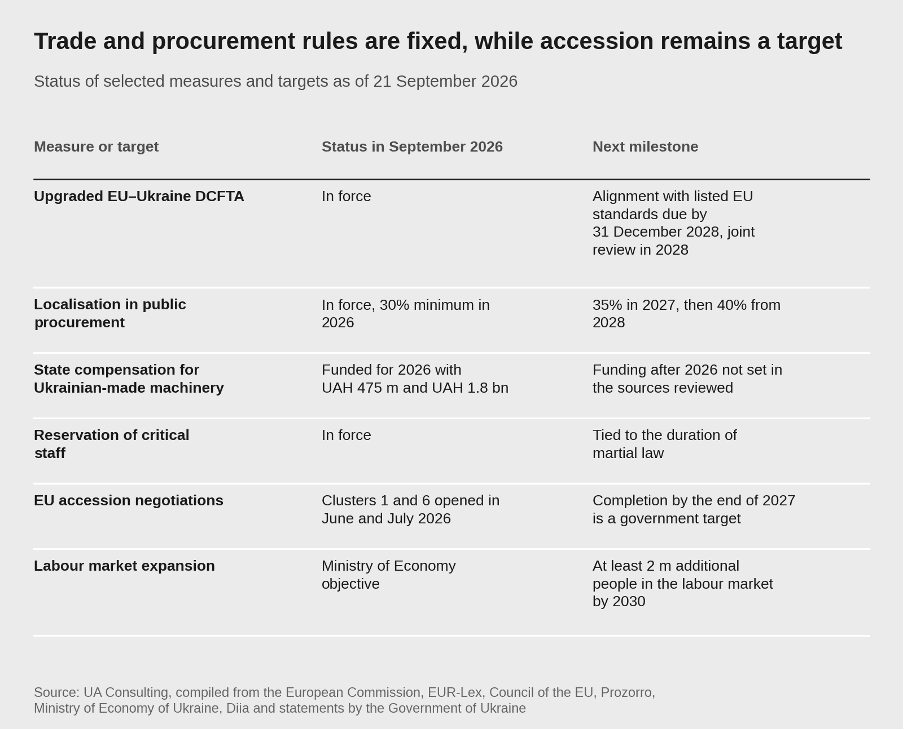
Sources: European Commission, EUR-Lex, Prozorro, Ministry of Economy of Ukraine, Diia, Council of the EU on cluster 1 and cluster 6, the Deputy Prime Minister for European integration and the Ministry of Economy's labour market priorities, compiled by UA Consulting.
Published forecasts cover the labour market more fully than they cover production. No projection of manufacturing output by the NBU or the government was found in the sources reviewed, and the only forecast for industry found is the World Bank's April 2026 outlook. It expects industrial value added to fall by 0.8% in 2026 and to grow by 8.0% in 2027 and 7.0% in 2028. That measure differs from the State Statistics Service production index, and none of the labour or industry forecasts reviewed extends beyond 2028.
For a production investment, the most decision-relevant changes are those with a defined timetable. The localisation schedule reaches its final step in 2028, the joint review of the upgraded DCFTA falls in the same year, and the labour outlook depends on whether the net return of migrants that the NBU expects from 2027 materialises. Accession remains a target rather than a schedule, since further negotiating clusters were still awaiting agreement among member states in September 2026.
Where the case for local production holds
Whether building a factory in Ukraine is viable now turns on the specific case more than on the national picture. The evidence supports local production where one rationale visibly carries the economics, the process tolerates the local resilience requirement at acceptable cost, and the occupations required can be recruited in the intended location. The case also has to stand if wages keep rising at the pace the NBU forecasts and supply restrictions recur.
The case remains open where the thesis is credible but one or two critical assumptions are unproven, usually accessible demand, staffing at the required skill level or the true cost of energy autonomy. Each can be established before capital is committed, which is feasibility work rather than a decision and costs a fraction of a wrong commitment. Testing whether a specific project is deliverable as designed is the role of our investment and project advisory work, and sector context is set out under Industrials & Manufacturing.
The case does not hold where it rests on wage arbitrage alone or on reconstruction demand that has not been traced to identified buyers. Optimistic utilisation and staffing assumptions the labour market will not support undermine it in the same way. So does a resilience requirement whose cost erases the advantage it was meant to protect, and so does a plan that needs more management attention than the group can supply. Continued import or contract production will sometimes be the economically superior answer, and remaining a supplier while the position clarifies is a legitimate outcome.
In the cases that hold, resilience is part of the operating model from the outset rather than a response to a first disruption. Duplicated capacity, dual sourcing, buffer inventory, backup utilities and transferable production each address a different failure, and the appropriate combination depends on the process, customer commitments and acceptable recovery time. Not every plant requires the most expensive of them.
The evidence to September 2026 separates two kinds of production case. The first already prices rising wages and the cost of resilience, and can therefore be tested on current conditions. The second needs those conditions to ease, and relies on forecasts that show relief only from 2027.
UA Consulting assesses whether production projects in Ukraine are feasible and deliverable before capital is committed. Discuss your production case.