On 3 March 2022 the Ukrainian parliament passed Law No. 2115-IX, which postponed the deadline for submitting accounting, financial and audit documents until three months after martial law ends. Martial law now runs to at least 31 October 2026. Obligations have returned in stages, with statistical and financial reporting to the statistics authorities resuming on 5 July 2025 and regulated disclosure by securities issuers on 28 August 2025, as set out in Baker McKenzie's guide to Ukrainian wartime legislation.
For more than three years, statutory reporting in Ukraine was lawfully detached from its own calendar while the commercial decisions behind it continued at ordinary speed. That gap is a useful starting point for a foreign owner, and the evidence below supports a narrower conclusion than the familiar advice to tighten control. Ukrainian conditions do not establish that foreign-owned subsidiaries need more centralised approval. What they establish is that several variables determining owner exposure now move faster than a standard group reporting cycle reveals, and that national averages conceal most of what matters at a single site. They also show that part of what a Ukrainian subsidiary can do with its cash and its workforce sits in dated entitlements that no financial statement carries. The practical consequence is that reporting frequency should follow the speed and materiality of each underlying variable rather than a single group timetable, while the questions that decide whether an owner is in control can only be answered inside the specific company.
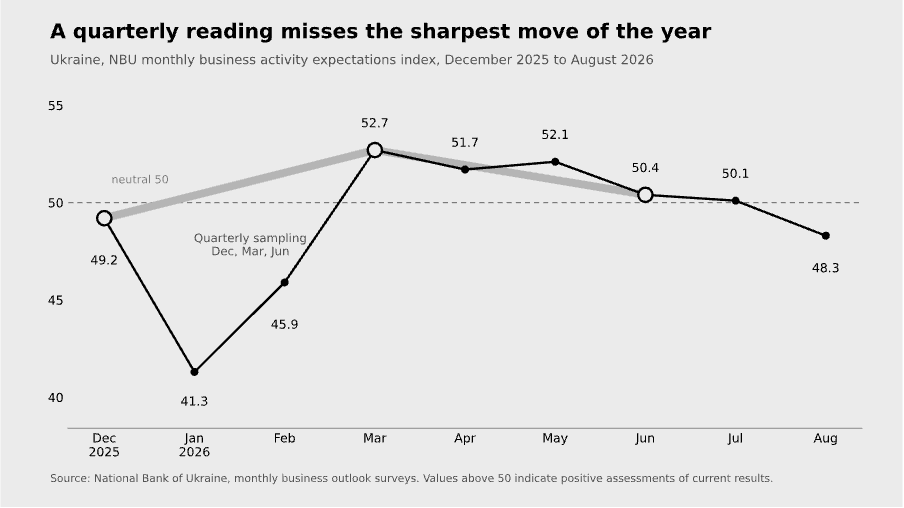
Ukraine's monthly business activity expectations index moved 11.4 points between December 2025 and August 2026 and crossed the neutral level twice, while a quarterly reading taken in December, March and June spans only 3.5 points. Source: National Bank of Ukraine monthly business outlook surveys.
The business often sees less far ahead than the group reviews it
The Institute for Economic Research and Policy Consulting surveys the same panel of mainly industrial enterprises every month. In its June 2026 survey, covering 471 companies across 21 regions, the average period covered by firm orders was 2.8 months, against 4.7 months a year earlier. Some 65% of respondents held orders covering no more than two months, and only 5% had orders running a year or more, down from 12% in June 2025. Coverage rose with company size, from 1.7 months at microenterprises to 3.8 months at large ones.
These figures describe the operating environment rather than any particular company, and what they establish is that forward commercial visibility inside many Ukrainian businesses is now shorter than the interval at which groups commonly review their subsidiaries. A quarterly cycle asks local management to account for a period longer than the one it could see when that period began. This does not make quarterly review wrong, but it does mean the parent receives an account of decisions taken under shorter visibility than the reporting rhythm suggests.
Conditions reset inside a single reporting period
The chart above tracks how companies rated their own current results month by month. Over the same nine months the National Bank's quarterly index of twelve-month expectations moved in the opposite direction, rising without interruption from 102.1 in the fourth quarter of 2025 to 105.8 in the first quarter of 2026 and 107.0 in the second. Confidence about the year ahead and conditions in the current month are separate measurements that can diverge for several quarters, and a parent reading only the forward-looking series would have seen steady improvement throughout the worst months on the ground.
Power supply shows both the speed of change and the limits of national averages. In the IER panel, the share of enterprises citing electricity, water or heat interruptions as a war-related obstacle fell from 48% in January 2026 to 19% in June. Companies that experienced outages lost an average of 5% of working time in May 2026, but that average concealed 18% in Cherkasy region, 16% in Dnipropetrovsk and 13% in Kharkiv, while 27% of companies had no outages at all. A single national figure tells a parent very little about its own site.
Logistics moved faster still, and difficulties transporting goods within Ukraine had already risen to 30% of IER respondents by June 2026. The following month, according to Ukrainian Sea Ports Authority figures reported by the Kyiv Post, 22 July was the first day since the maritime corridor opened in 2023 on which no vessel entered the Greater Odesa ports. Seven vessels entered in the first eleven days of August, against 169 across the whole of July. For an exporter, the route to market changed within a fortnight.
Independent verification became possible again in January 2026
Owner visibility also depends on whether the parent can check anything against a source outside the management line, and in Ukraine that capability was legally suspended and then legally restored. Access to public electronic registers was restricted from March 2022 under Cabinet of Ministers Resolution No. 263.
Ministry of Justice Order No. 1462/5 of 13 April 2022 suspended open data entirely, and Order No. 423/5 of 31 January 2023 partially restored it while keeping the Unified State Register of Legal Entities closed. Law No. 4576-IX of 21 August 2025 then obliged the Ministry to publish that register as open data, and the Ministry of Justice restored publication from 19 January 2026, with datasets refreshed weekly. The same law narrows disclosure elsewhere, removing precise location data for real estate owned by legal entities and allowing entries connected with defence production to be restricted.
For almost four years a foreign parent could not independently confirm through open data the registered particulars of its own Ukrainian entity, the identity of the person holding signing authority, or the ownership behind a proposed counterparty. That capability returned in January 2026, which makes this one of the few visibility questions in Ukraine where the answer changed by a dated legal act rather than by management effort. It is worth establishing which verification routines were built around the closed period and have never been revisited since.
How much cash the parent can take out is not a balance-sheet figure
Dividend repatriation reopened on 13 May 2024 under the National Bank's largest easing package since 2022, initially for profits earned from 1 January 2024 and subject to a cap equivalent to one million euros a month. The regulator has since built a layer of company-specific entitlements on top of the general rules. An investment limit reflects foreign currency contributed to charter capital from May 2025, and a loan limit effective 14 January 2026 reflects foreign currency loans credited after 1 January 2026. An additional limit introduced with the package effective 11 August 2026 reflects qualifying defence contributions, and limits may now be shared with related Ukrainian companies by written consent, provided the transactions run through a single designated bank.
The consequence for a foreign parent is specific. The amount that can lawfully leave the subsidiary depends on a dated record of the group's own past capital and lending decisions, held bank by bank, rather than on profit or cash balance. That record appears in no statutory statement, and the rules governing it have changed in successive packages since May 2024. Settlement deadlines work in the same way, since export and import settlements must complete within 180 days, reduced to 120 days for certain agricultural exports and extended to 270 days for specialised machinery. An unsettled export receivable therefore runs against a regulatory clock as well as a commercial one, including through a period when vessels were not sailing.
The scale of the question is visible in the aggregates. National Bank balance of payments data put net foreign direct investment at 2.4 billion dollars in 2025, of which 1.0 billion was reinvested earnings, against 3.7 billion and 2.6 billion respectively in 2024. The aggregate says nothing about any individual subsidiary, but it does show that decisions about whether earnings stay in Ukraine are being taken actively rather than by default.
Exposure is fixed at the commitment, not at the payment
The principle that control attaches to obligations rather than disbursements is long established and not specific to Ukraine. The IMF technical note on commitment controls describes commitment as the stage at which expenditure is effectively determined, with the payment that follows confirming a decision already taken.
What Ukrainian conditions change is how quickly a commitment becomes irreversible. Rerouting cargo through the Danube or by rail, accepting revised delivery deadlines, contracting for back-up generation or agreeing new supplier terms are decisions taken within days once a route closes or a grid fails. A parent that reviews payments above a threshold is observing the final step of a sequence that concluded earlier. The AICPA and CIMA Global Management Accounting Principles treat relevance as including availability to decision-makers when they need it, which makes timeliness part of the definition rather than a refinement of it.
Delegated authority has to cover decisions that cannot wait
Tighter centralisation is not automatically safer. Where conditions reset inside a reporting period, routing routine decisions through headquarters slows the response and moves accountability away from the people holding the facts. The useful question is which decisions can be taken locally without materially altering capital exposure, risk or strategic direction, and the answer differs between a distributor, a factory and a software business.
Staff continuity is one area where the decision itself carries an expiry date. Reservation from mobilisation runs for up to twelve months and is generally capped at half of the employees liable for military service. It requires electronic submission through the Diia portal and a salary of at least three times the minimum wage, and it must be cancelled within ten business days if statutory limits are exceeded. Labour shortage caused by conscription or migration was the leading war-related obstacle for 71% of IER respondents in June 2026. Which reservations are running, and when they lapse, is operating information rather than an administrative detail. Where reporting, escalation and control routines need rebuilding rather than redesigning, that becomes a matter for operations consulting and execution support rather than another layer of approval.
What market evidence cannot settle for a particular subsidiary
No national dataset records how many foreign-owned Ukrainian subsidiaries report late, exceed delegated authority or leave headquarters with an incomplete picture. Those questions are answered inside a specific company or they are not answered at all, and that absence is a boundary of the analysis rather than a gap to be filled with plausible assumptions.
What external evidence can do is tell a parent where to look. The further headquarters sits from the operation, the more it depends on the reporting it is trying to test, which strengthens the case for independent owner-side oversight. Where material information cannot be reconciled against operating evidence the owner can verify independently, a judgement with capital consequences is resting on a single source.
Much of what remains is ordinary multinational management. Variance explanation, consistent definitions, reconciliation between operational and financial data and clearly reserved matters are not Ukrainian questions. Where unexplained variance persists after the information problem has been resolved, the subject has changed from visibility to performance, and diagnosing an underperforming Ukrainian operation is a different examination altogether.
If you own or oversee a Ukrainian business and need an independent senior view on what your reporting is telling you, talk to UA Consulting.